
Maximizing the tax benefits of a 529 plan can significantly enhance your savings strategy for future educational expenses. As one of the most effective tools for funding education, 529 plans offer unique tax advantages that can ease the financial burden of college or K-12 tuition. Understanding how to leverage these benefits fully is crucial for both seasoned investors and new savers alike. In this article, we will explore key strategies to optimize your 529 plan contributions, withdrawals, and growth, ensuring that you make the most of this powerful savings vehicle. With a confident grasp of these tactics, you’ll be well-equipped to support your educational goals while maximizing your financial potential.
Understanding the Tax Advantages of 529 Plans
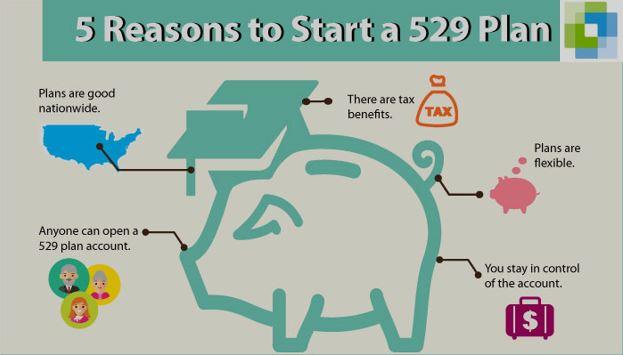
One of the most compelling benefits of 529 plans is their tax-free growth potential. Earnings on contributions are not subject to federal income tax when used for qualified education expenses, allowing investments to compound more efficiently over time. Furthermore, many states offer additional tax incentives, such as deductions or credits on state income taxes, which can further enhance the financial benefits of these plans.
- Tax-free withdrawals: As long as the funds are used for eligible expenses, like tuition, books, or room and board, withdrawals are not taxed.
- Gift tax advantages: Contributions to a 529 plan are considered gifts for tax purposes, allowing individuals to contribute up to $17,000 per year (or $34,000 for married couples) without incurring gift tax. Additionally, the IRS allows a special provision to “superfund” a 529 plan by contributing five years’ worth of gifts at once.
- Estate tax benefits: Assets in a 529 plan are removed from the contributor’s taxable estate, potentially reducing estate taxes for high-net-worth individuals.
By leveraging these tax advantages, families can strategically plan for future educational expenses while minimizing their tax burden, making 529 plans a powerful tool in education funding.
Optimizing Contributions for Maximum Tax Efficiency
When it comes to maximizing the tax benefits of a 529 plan, strategic contributions play a crucial role. First, it’s essential to understand the annual gift tax exclusion. By contributing up to the annual limit per beneficiary, you can avoid incurring any gift tax consequences. In 2023, this amount is $17,000 per individual donor or $34,000 for married couples. For those looking to supercharge their contributions, the five-year gift tax averaging option allows you to front-load up to five times the annual exclusion amount, effectively making a substantial impact on the plan’s growth potential without exceeding gift tax limits.
Another critical factor is taking advantage of state tax deductions or credits. Many states offer tax incentives for contributions to their 529 plans, providing an immediate tax benefit. It’s vital to be aware of the specific requirements and limits of your state’s program, as these can vary significantly. Additionally, consider the timing of your contributions; making them early in the year can maximize the potential for tax-free earnings growth over time. By aligning contributions with these strategies, you can optimize the tax efficiency of your 529 plan, ensuring that more of your funds go towards educational expenses rather than taxes.
Strategic Timing for Withdrawals to Minimize Tax Impact
Timing your withdrawals from a 529 plan is crucial for minimizing tax liabilities and maximizing benefits. Strategically scheduling withdrawals to align with educational expenses can prevent unnecessary tax burdens. For instance, ensure that withdrawals correspond directly with the payment of qualifying expenses such as tuition, fees, and textbooks within the same tax year. This alignment helps in keeping the distributions tax-free, as any mismatch could result in taxable income and penalties.
It’s also wise to consider the sequence of withdrawals if you have multiple accounts or sources of funding. Prioritize tapping into your 529 plan before utilizing any loans or other taxable income sources. This strategy not only capitalizes on the tax-free growth and withdrawals of the 529 plan but also maintains your financial flexibility. Some key tips include:
- Matching withdrawals with specific expenses to avoid tax pitfalls.
- Tracking expenses meticulously to provide clear documentation if needed.
- Consulting with a financial advisor to plan withdrawals over the course of your beneficiary’s education.
By employing these strategies, you can effectively manage your 529 plan to its fullest tax advantage.
Leveraging State-Specific Benefits for Enhanced Savings
To make the most of your 529 plan, it’s essential to understand the unique benefits that each state offers. While some states provide tax deductions or credits for contributions to any 529 plan, others may offer additional incentives for investing in their specific state-sponsored plans. Here are a few strategies to help you maximize these state-specific benefits:
- Explore State Tax Deductions: Investigate whether your state offers a tax deduction or credit for contributions to a 529 plan. Even if your state doesn’t offer a deduction, consider whether the benefits of another state’s plan outweigh the tax advantages.
- Compare Plan Features: Evaluate the investment options, fees, and performance of your state’s plan against others. Sometimes, the cost savings from lower fees or superior performance can surpass state tax benefits.
- Consider Multiple Plans: You aren’t limited to one 529 plan. If your state offers tax benefits, contribute enough to capture those benefits, then consider other plans for additional savings.
By strategically choosing where to invest, you can significantly enhance your savings, ensuring you get the most out of your 529 plan investments. Remember, the right approach depends on your financial goals and the specific offerings in your state.