
In the evolving landscape of financial planning, government-sponsored education savings accounts have emerged as a pivotal tool for families seeking to secure their children’s educational futures. These accounts, often characterized by tax advantages and flexible contribution options, provide a strategic avenue for long-term planning, empowering parents to manage the escalating costs of education with foresight and confidence. As education expenses continue to rise, understanding the intricacies of these savings accounts becomes essential for families aiming to alleviate future financial burdens while maximizing the potential for educational success. This article delves into the critical role these accounts play in comprehensive financial planning, offering insights into their benefits, limitations, and strategic implementation to ensure that educational aspirations are met without compromising financial stability.
Understanding Government Sponsored Education Savings Accounts Benefits and Opportunities
Government-sponsored education savings accounts offer a plethora of benefits and opportunities that can significantly aid in long-term financial planning for education. These accounts, such as 529 plans in the United States, are designed to help families save for future educational expenses with tax advantages. Key benefits include:
- Tax-free growth: Earnings on the contributions grow tax-free, allowing the savings to accumulate more efficiently over time.
- Tax-free withdrawals: Funds withdrawn for qualified education expenses are not subject to federal taxes, maximizing the value of your savings.
- State tax deductions: Many states offer tax deductions or credits for contributions made to these accounts, providing immediate tax relief.
In addition to these benefits, education savings accounts present opportunities for strategic financial planning. They can be used to hedge against rising education costs, ensuring that future generations have access to the education they need without the burden of student loans. Furthermore, they offer flexibility, as some plans allow for changes in beneficiaries or even the ability to roll over funds to another account, such as a sibling’s or relative’s, if the original beneficiary does not use the funds. These features make government-sponsored education savings accounts a versatile tool in any family’s financial toolkit.
Strategic Approaches to Maximize Education Savings Account Growth
To effectively grow your education savings account, it’s crucial to adopt a strategic approach that leverages both government incentives and smart financial planning. Diversification is key. By investing in a mix of stocks, bonds, and mutual funds, you can mitigate risks and optimize returns. Additionally, take advantage of tax benefits offered by government-sponsored accounts, such as tax-free growth and withdrawals for educational expenses. Regularly review and adjust your investment portfolio to align with changing market conditions and your evolving financial goals.
Consider the following strategies to enhance your account’s growth potential:
- Consistent Contributions: Make regular contributions to your account, even if they are small. Over time, these will compound and significantly boost your savings.
- Government Matching Programs: Explore any available government matching contributions or grants that can provide an immediate boost to your savings.
- Automatic Transfers: Set up automatic transfers from your checking account to your education savings account to ensure consistent funding.
- Regular Account Reviews: Conduct periodic reviews of your account to assess performance and make necessary adjustments.
By implementing these strategies, you can effectively maximize the growth of your education savings account and ensure a financially secure future for educational pursuits.
Integrating Education Savings Accounts into Comprehensive Long Term Financial Plans
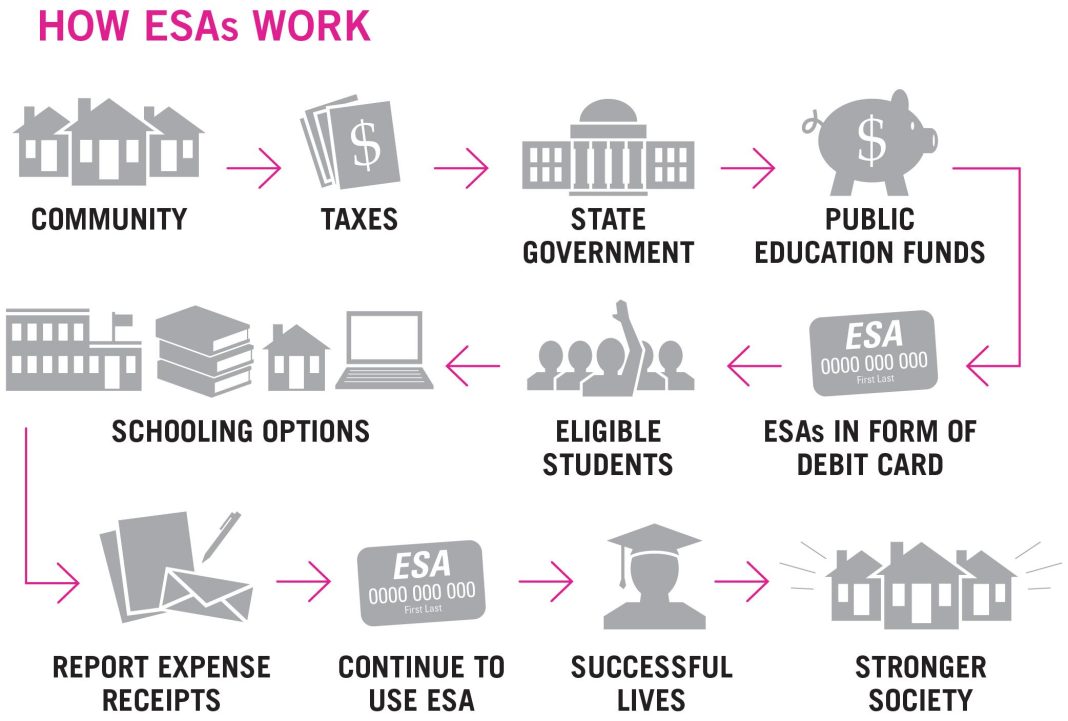
Education Savings Accounts (ESAs) serve as a vital component in crafting a robust long-term financial strategy. These government-sponsored accounts offer tax advantages that make them an attractive option for parents and guardians planning for their children’s educational futures. When integrated into a comprehensive financial plan, ESAs not only provide a structured approach to saving for education but also align with broader financial goals such as retirement planning and asset management. Here’s how they can be effectively utilized:
- Tax Benefits: Contributions to ESAs grow tax-free, and withdrawals are also tax-free when used for qualified educational expenses, providing a significant financial advantage.
- Flexibility: Unlike some other educational savings plans, ESAs allow for a wide range of investment options, enabling account holders to tailor their investment strategy according to their risk tolerance and financial objectives.
- Transferability: If the beneficiary chooses not to pursue higher education, the account can often be transferred to another family member, ensuring that the savings are not wasted.
Incorporating ESAs into a long-term financial plan requires careful consideration of current financial status, future educational costs, and overall financial goals. By understanding the unique benefits and strategic advantages of ESAs, individuals can ensure they are maximizing their financial potential while securing a bright educational future for their children.
Expert Recommendations for Optimizing Education Savings Account Contributions
To make the most of your government-sponsored education savings accounts, consider these expert-backed strategies. First, start early. The power of compound interest means that even modest contributions can grow significantly over time. Begin contributions as soon as possible, even if the amounts are small.
- Maximize Contributions: Aim to contribute the maximum allowable amount each year. This not only maximizes the potential growth of your savings but can also provide tax advantages depending on the type of account.
- Automate Savings: Set up automatic contributions from your paycheck or bank account. This ensures consistent savings and reduces the temptation to skip contributions.
- Diversify Investments: Within your education savings account, choose a diversified mix of investments. Consider age-based or target-date funds that adjust their risk profile as the beneficiary gets closer to college age.
- Review and Adjust: Regularly review your account’s performance and adjust your strategy as needed. Life changes, such as a new job or additional children, might require changes in your savings approach.
By following these expert recommendations, you can ensure that your education savings accounts are optimized for the long-term benefit of your child’s education.