
In the journey of life, milestone purchases—be it buying a home, funding a child’s education, or planning a dream vacation—represent significant achievements and aspirations. Yet, these substantial financial commitments can often seem daunting without a structured approach. Effective financial goal setting is the cornerstone of transforming these dreams into attainable realities. By adopting a strategic mindset and employing practical techniques, anyone can navigate the complexities of financial planning with confidence. This article will guide you through the essential steps to establish clear, achievable goals, and equip you with the tools needed to successfully plan for those important milestone purchases. Prepare to embark on a journey toward financial empowerment, where each step brings you closer to realizing your dreams.
Identifying Key Milestone Purchases and Setting Priorities
When embarking on the journey of financial goal setting for significant purchases, it’s essential to first identify which purchases are truly pivotal in your life. These could range from buying a home, financing education, to planning a dream vacation. Each milestone represents a stepping stone towards achieving your broader life goals. To streamline this process, consider creating a comprehensive list of potential purchases and categorize them based on urgency and impact.
- Urgency: Determine which purchases need immediate attention versus those that can be deferred.
- Impact: Assess how each purchase will affect your financial health and life satisfaction.
Once these priorities are set, align them with your financial capacity and savings plan. By setting clear priorities, you not only ensure that your funds are allocated efficiently but also prevent impulsive spending. Regularly revisiting and adjusting your list can help accommodate life changes and maintain financial stability.
Crafting a Realistic Financial Timeline for Your Goals
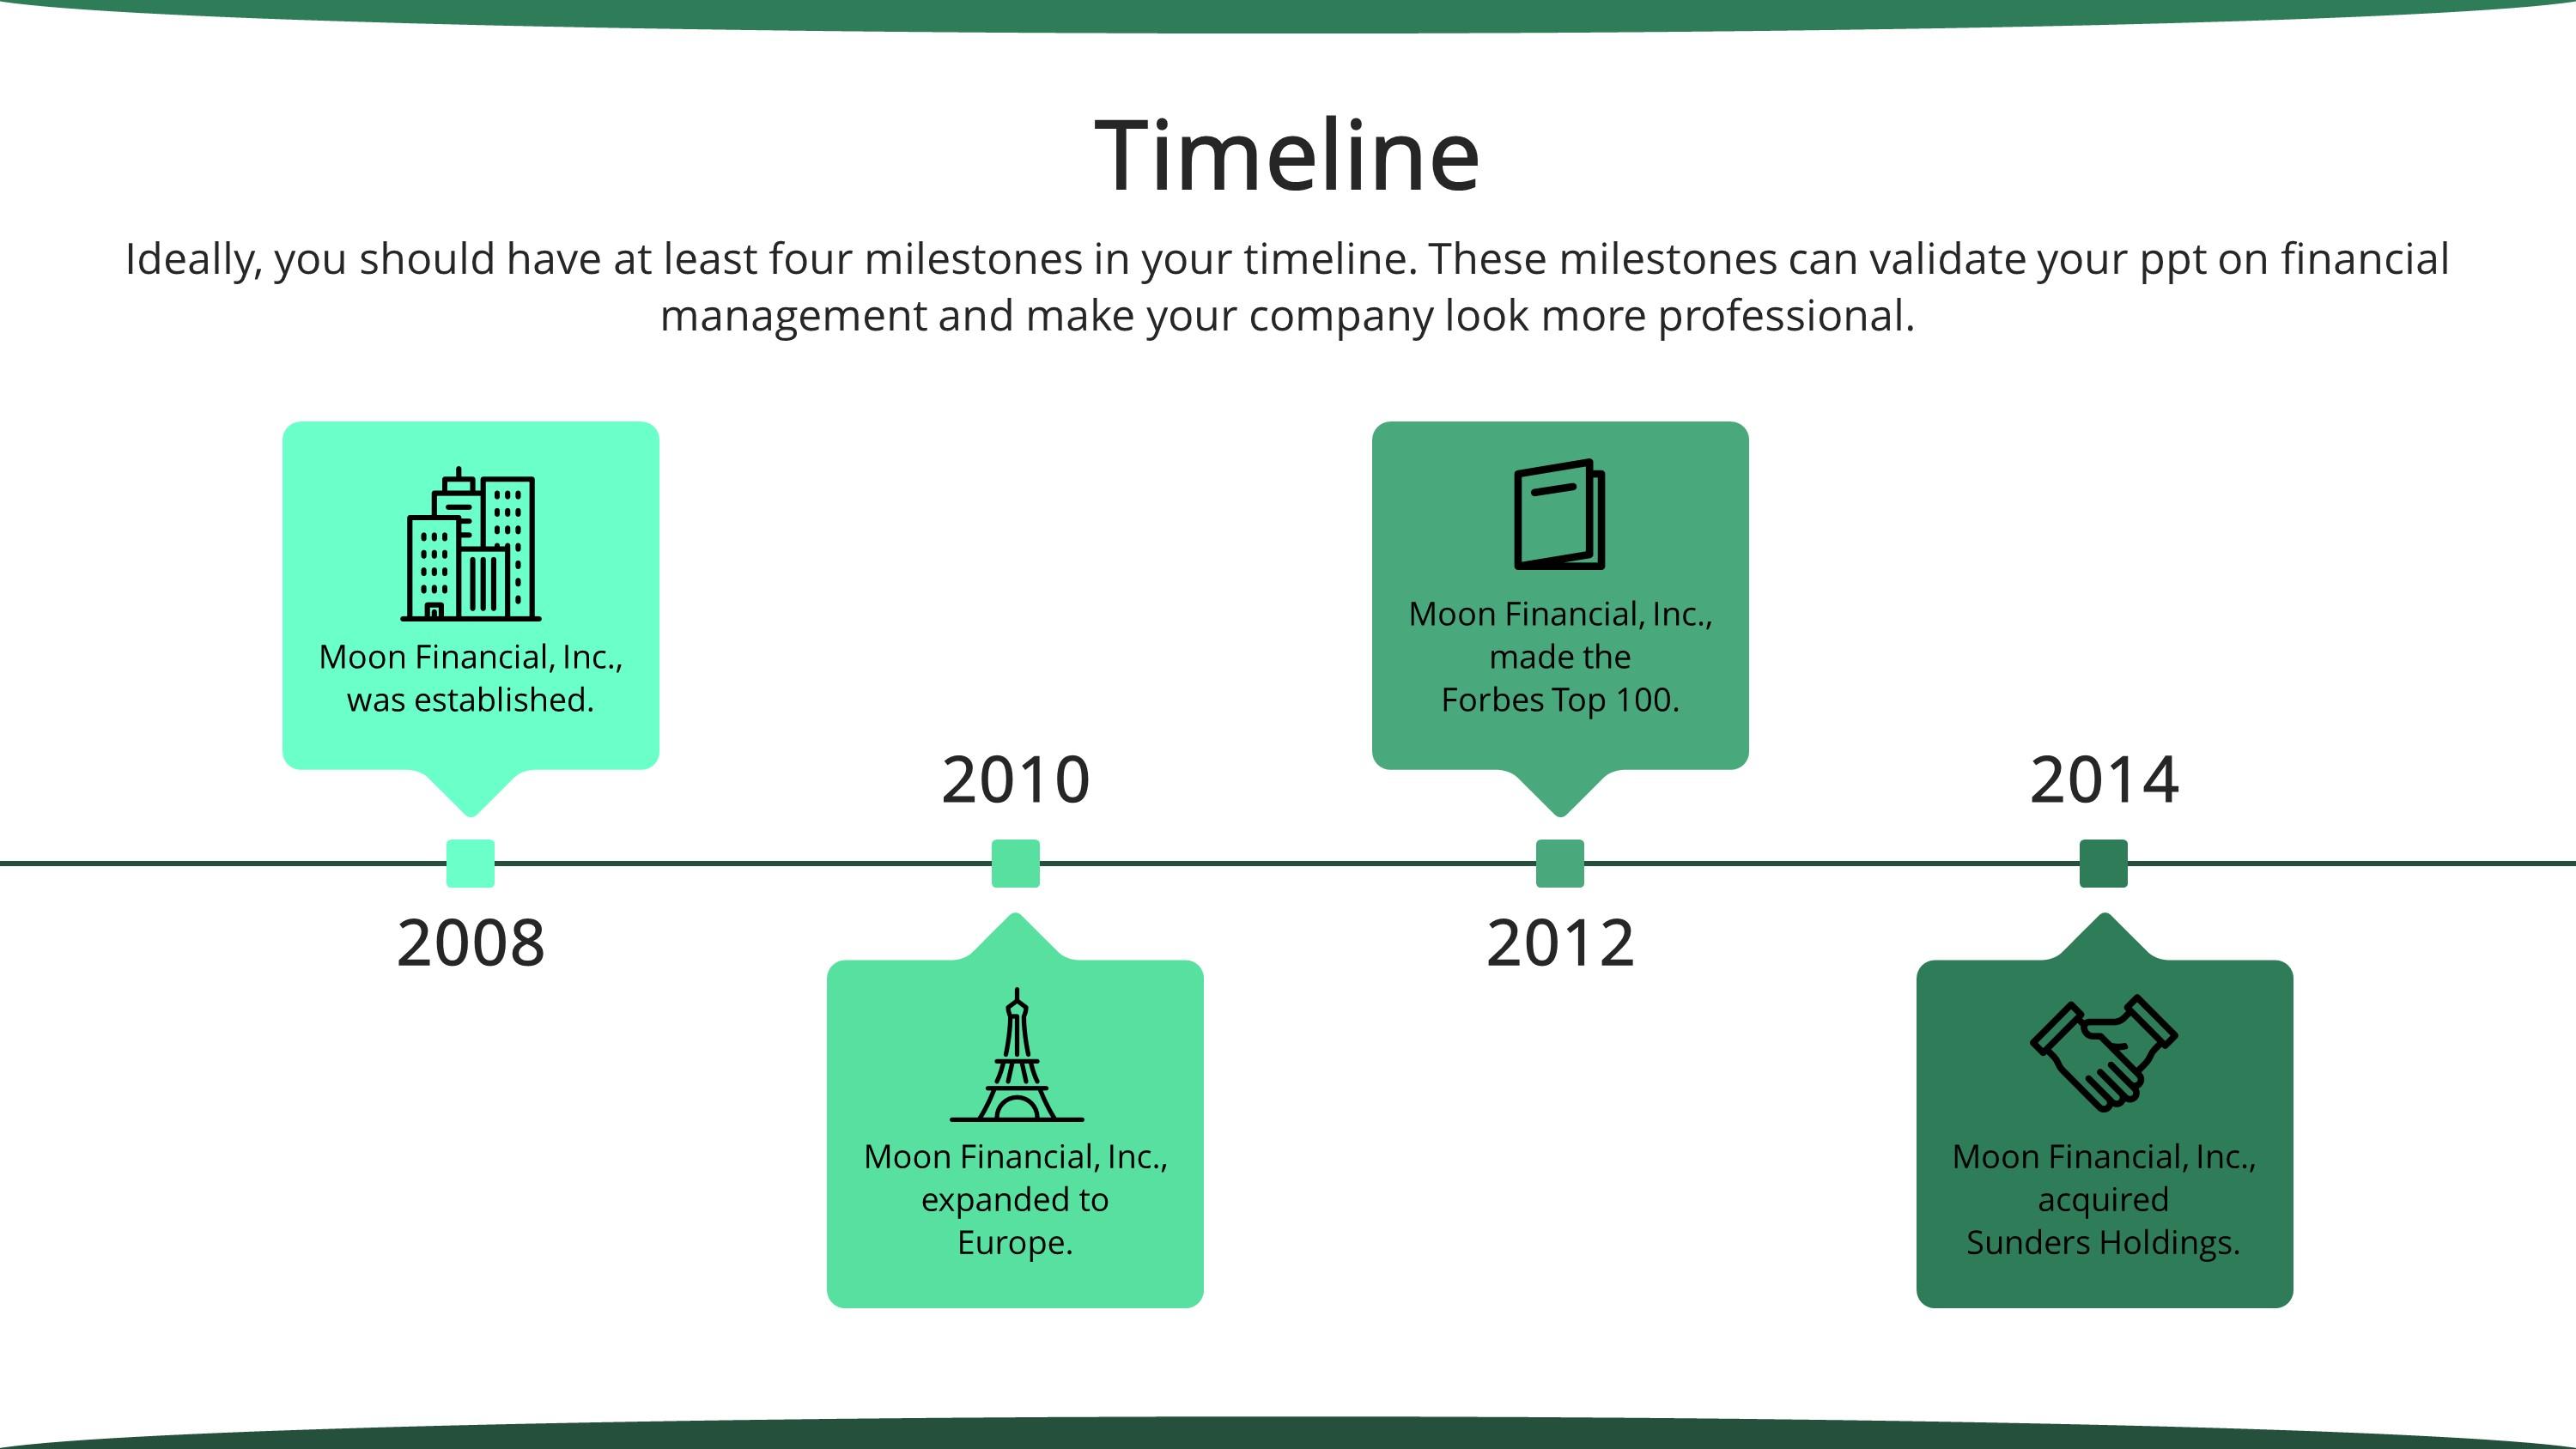
When it comes to achieving your financial aspirations, setting up a timeline that mirrors your life’s pace and priorities is crucial. Start by identifying your milestone purchases, such as a new home, car, or even a dream vacation. Once you’ve pinpointed these goals, break them down into manageable time frames. Consider asking yourself:
- Short-term goals: What do I want to achieve in the next 1-3 years?
- Medium-term goals: What purchases should I plan for in the next 3-5 years?
- Long-term goals: What major milestones are set for 5+ years from now?
For each goal, establish a realistic savings target and calculate how much you need to save monthly to meet your deadlines. This approach not only keeps you focused but also allows flexibility to adapt as your circumstances change. Leverage tools like budgeting apps and financial planners to keep track of your progress and ensure you’re on track to achieve these milestone purchases without financial strain.
Building a Flexible Budget to Accommodate Milestone Purchases
Creating a budget that remains adaptable while accommodating significant purchases can transform financial stress into strategic success. Start by identifying your milestone purchases, whether it’s a new home, a car, or a dream vacation. Then, incorporate these into your budget using a flexible approach that allows for adjustments as your financial situation evolves. Focus on setting clear financial goals and breaking them down into manageable, measurable steps. This can involve:
- Categorizing your expenses into fixed and variable to easily identify areas where you can save.
- Allocating a specific portion of your income towards a dedicated savings fund for each milestone.
- Regularly reviewing and adjusting your budget to reflect changes in income or unexpected expenses.
- Leveraging tools and apps that provide insights and help track your progress towards these goals.
By maintaining a dynamic budget, you not only prepare for these significant expenses but also create a financial plan that is resilient and responsive to life’s changes.
Utilizing Financial Tools and Resources for Effective Goal Tracking
Achieving significant financial milestones requires more than just saving money; it demands strategic planning and utilization of specialized financial tools. Budgeting apps and financial planning software can serve as invaluable allies in this journey. These tools allow you to set specific goals, track your progress, and adjust your plans as needed. They provide visual insights through charts and graphs, making it easier to comprehend your financial standing and the steps required to reach your targets. With the aid of these resources, you can create a dynamic plan that evolves with your financial situation.
Beyond digital tools, leveraging a mix of traditional financial resources can amplify your goal-setting process. Consider the following:
- Consulting with a financial advisor: Gain expert insights tailored to your financial goals.
- Using spreadsheets for manual tracking: Offers flexibility and customization for detailed financial analysis.
- Engaging in financial literacy programs: Enhances understanding of effective saving strategies and investment opportunities.
By integrating both modern and traditional resources, you position yourself to not only set realistic milestones but also to achieve them with confidence and precision.