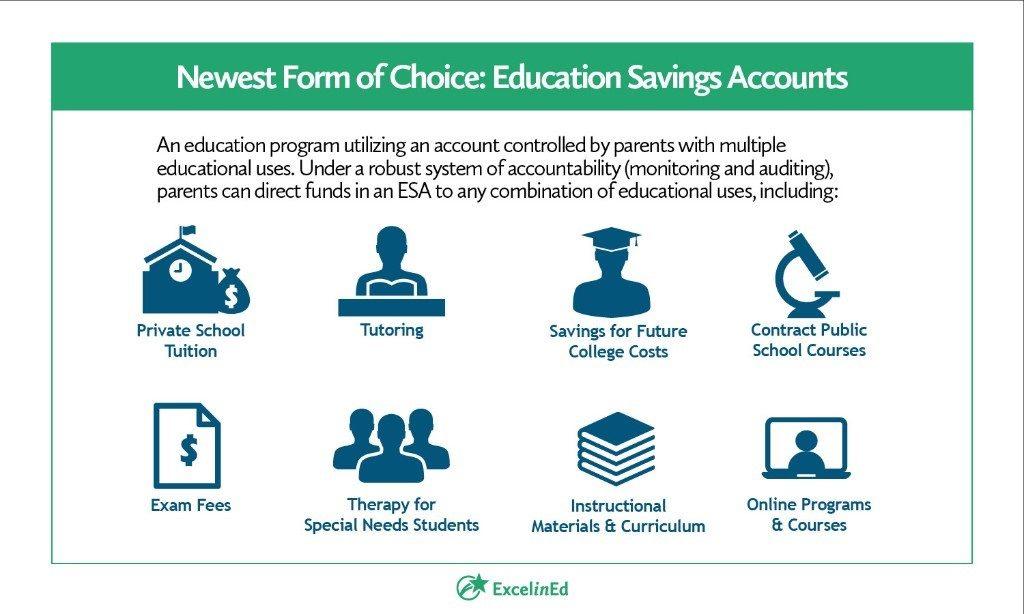

In today’s rapidly evolving educational landscape, parents are increasingly seeking innovative ways to ensure their children receive the best possible start in life. One of the most powerful tools available to achieve this goal is the Education Savings Account (ESA). As a savvy parent, understanding the intricacies of ESAs can unlock a world of opportunities for your child’s educational journey, from primary schooling through to higher education. This guide will demystify the concept of Education Savings Accounts, equipping you with the knowledge to make informed decisions that align with your family’s financial planning and educational aspirations. Dive in to discover how ESAs can be a game-changer in securing your child’s academic future, offering flexibility, control, and potential tax benefits that traditional savings methods may not provide.
Understanding the Basics of Education Savings Accounts
Education Savings Accounts (ESAs) are a powerful tool for parents looking to invest in their child’s future. Unlike traditional savings plans, ESAs offer flexibility and tax advantages that can significantly ease the financial burden of educational expenses. Here are some key features to consider:
- Tax Benefits: Contributions to an ESA grow tax-free, and withdrawals are also tax-free as long as they’re used for qualifying educational expenses. This can include tuition, books, and even certain supplies.
- Flexibility: ESAs can be used for a wide range of educational needs, not just college. This includes K-12 tuition and even some homeschooling expenses, providing a comprehensive solution for various educational paths.
- Contribution Limits: While the annual contribution limit is modest, often around $2,000 per beneficiary, the long-term benefits can be substantial due to compound interest and tax-free growth.
Understanding these features can help parents make informed decisions about investing in their child’s education, ensuring they are well-prepared for future academic endeavors.
Maximizing Benefits Through Strategic Contributions
To truly harness the potential of Education Savings Accounts (ESAs), parents should approach contributions with a strategic mindset. Consider these key strategies to maximize your benefits:
- Consistent Contributions: Regular deposits, even small ones, can significantly boost the growth of your ESA over time. Setting up automatic transfers can ensure consistency and help avoid the temptation to skip months.
- Leverage Matching Programs: Some employers or states offer matching contributions for education savings. Check if you qualify for such programs and make sure to take full advantage of them.
- Optimize Investment Options: ESAs often come with a variety of investment choices. Analyze the risk levels and potential returns of each option to align them with your long-term educational goals.
By thoughtfully planning your contributions and making informed decisions, you can significantly enhance the financial resources available for your child’s education, paving the way for a brighter academic future.
Choosing the Right Education Savings Account for Your Family
When navigating the myriad of education savings accounts available, it’s crucial to understand the specific needs of your family and the nuances of each option. Start by considering the 529 Plan, a tax-advantaged investment account designed to encourage saving for future education costs. It offers flexibility, allowing funds to be used for a wide range of educational expenses. Alternatively, the Coverdell Education Savings Account might be suitable if you’re looking for broader investment choices and the ability to cover elementary and secondary education expenses. However, keep in mind its contribution limits and income restrictions.
Before making a decision, evaluate your financial situation and future education goals. Ask yourself:
- What is the anticipated cost of education?
- How much can you realistically contribute annually?
- Are you looking for an account that covers specific types of educational expenses?
By addressing these questions, you’ll be better equipped to choose an account that aligns with your family’s educational aspirations and financial capabilities.
Avoiding Common Pitfalls in Managing Education Savings Accounts
When managing Education Savings Accounts (ESAs), it’s essential to navigate potential missteps that can affect your child’s future education. Here are some key strategies to keep in mind:
- Understand the Rules: Each type of ESA has specific regulations regarding contributions, withdrawals, and tax implications. Familiarize yourself with these to maximize benefits and avoid penalties.
- Monitor Investment Choices: Diversification is crucial. Avoid putting all your funds into one investment option. Instead, assess and adjust your portfolio periodically to align with market changes and your financial goals.
- Stay Informed About Educational Costs: Regularly update your knowledge of tuition and associated costs. This ensures your savings are on track to meet future expenses without unexpected shortfalls.
- Consider State-Specific Benefits: Some states offer additional tax advantages or incentives for specific ESAs. Research these to take full advantage of available benefits.
By being proactive and informed, you can effectively manage your ESA and secure a brighter educational future for your child.