In today’s fast-paced financial landscape, credit cards often seem like a convenient solution to immediate monetary needs. However, for individuals striving to eliminate debt, reliance on credit can quickly become a double-edged sword, exacerbating financial burdens rather than alleviating them. This article serves as a practical guide for those committed to breaking the cycle of debt by avoiding credit card usage altogether. With a confident approach and actionable strategies, we will explore effective methods to manage expenses, cultivate discipline, and achieve financial independence. By adopting these practices, you can empower yourself to make informed decisions, regain control over your finances, and pave the way to a debt-free future.
Master the Art of Budgeting for a Debt-Free Life
To successfully eliminate credit card usage while tackling your debt, it’s essential to establish a solid financial plan that prioritizes your necessities and goals. Begin by crafting a comprehensive budget that accurately reflects your income and expenditures. Identify and categorize your expenses into essential and non-essential items, allowing you to focus on cutting unnecessary costs. Track every penny with a budgeting app or a simple spreadsheet to ensure transparency and accountability.
Consider implementing the following strategies to keep your credit card out of reach:
- Switch to cash or debit cards for everyday purchases to avoid the temptation of overspending.
- Set up automatic bill payments from your bank account to prevent late fees and interest charges.
- Build a small emergency fund to cover unexpected expenses without resorting to credit cards.
- Focus on increasing your income through side hustles or freelancing, directing any additional earnings towards debt repayment.
By adopting these practices, you’ll cultivate a disciplined approach to spending, paving the way to a debt-free life.
Embrace Cash-Only Transactions to Stay Accountable
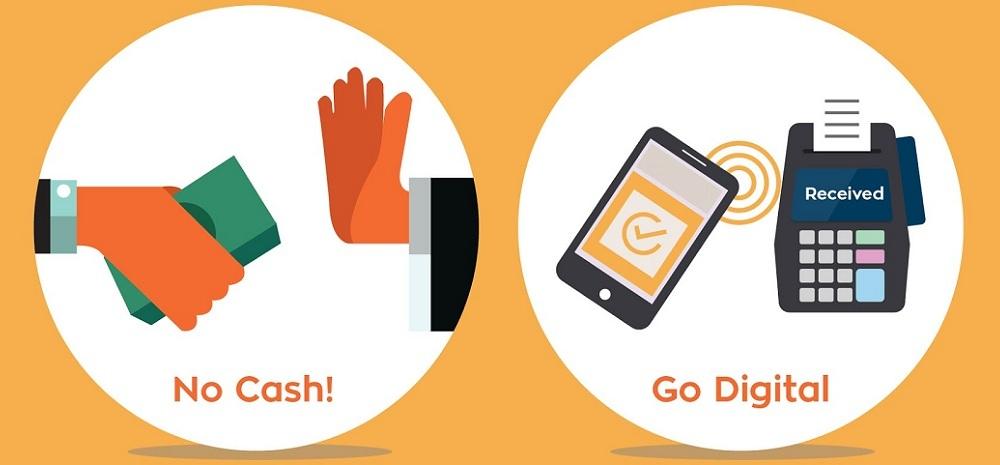
Transitioning to a cash-only lifestyle can be a powerful strategy to keep yourself accountable during your debt payoff journey. With cash, you can physically see your money leaving your hands, making each purchase more tangible and intentional. This method encourages you to plan your spending more carefully, ensuring that every dollar aligns with your debt reduction goals. Here are some tips to help you make the shift:
- Create a Budget: Allocate specific amounts of cash for different categories like groceries, entertainment, and transportation. Stick to these amounts to prevent overspending.
- Use Envelopes: Organize your cash by using envelopes for each spending category. This visual representation of your budget helps you track your spending in real-time.
- Leave Credit Cards at Home: By not carrying credit cards, you eliminate the temptation to spend beyond your means, ensuring that you stay on track with your financial plan.
Adopting a cash-only approach requires discipline, but it can drastically reduce the urge to impulse buy, helping you stay committed to your financial goals. Remember, the key is to consistently remind yourself of the larger picture—becoming debt-free.
Explore Alternative Payment Methods to Credit Cards
- Debit Cards: Embrace the simplicity of debit cards. They draw directly from your bank account, ensuring you only spend what you have. This can be a powerful tool in maintaining a budget and avoiding additional debt.
- Mobile Payment Apps: Apps like Venmo, PayPal, or Apple Pay offer a seamless and secure way to handle transactions. With their increasing acceptance at various merchants, these apps allow you to manage your finances in real-time and avoid the temptation of credit.
- Prepaid Cards: Load them with a specific amount and use them just like a debit card. These are particularly useful for setting spending limits and can be an excellent way to stick to a budget.
- Bank Transfers: For larger purchases or bills, consider direct bank transfers. Many vendors offer this option, which can be both secure and straightforward, keeping your spending aligned with your actual cash flow.
By exploring these alternatives, you can maintain financial discipline and reduce reliance on credit cards, all while making strides toward paying off debt. Leveraging these methods not only helps in managing current expenses but also instills a sense of financial responsibility, paving the way for a debt-free future.

Cultivate Mindful Spending Habits for Long-Term Success
Embracing mindful spending is essential when striving to pay off debt without relying on credit cards. Begin by scrutinizing your expenses to differentiate between needs and wants. Create a detailed budget that focuses on essential expenditures while setting aside funds for debt repayment. This strategy requires discipline, but by maintaining a clear picture of your financial landscape, you can allocate resources more effectively.
To support this journey, consider implementing these practices:
- Track Your Expenses: Keep a daily log of your spending to identify patterns and areas for potential savings.
- Prioritize Payments: Allocate payments towards high-interest debts first to minimize overall interest costs.
- Automate Savings: Set up automatic transfers to a savings account to build a financial cushion, reducing the temptation to use credit cards.
- Embrace a Cash-Only Lifestyle: Use cash for daily expenses to create a tangible connection with your spending habits.
By adopting these practices, you can cultivate a mindful approach to spending, paving the way for financial stability and success.