
In today’s fast-paced world, managing family finances can often feel like navigating a labyrinth, especially when debt looms large on the horizon. Yet, the path to financial freedom begins with a single, decisive step: crafting a family budget that prioritizes debt repayment. This article will guide you through the process of building a robust budget designed not only to manage your everyday expenses but also to strategically tackle debt head-on. With a confident approach and clear strategies, you can transform your financial landscape, ensuring stability and peace of mind for your family’s future. Whether you’re dealing with student loans, credit card balances, or a mortgage, this guide will empower you to take control of your finances and pave the way to a debt-free life.
Prioritize and Categorize Your Expenses
To effectively channel your resources toward debt repayment, it’s crucial to organize your expenses into manageable categories. Start by distinguishing between your essential and non-essential expenditures. Essential expenses are those you can’t live without, such as:
- Housing (rent or mortgage)
- Utilities (electricity, water, gas)
- Groceries
- Transportation
- Healthcare
Once you have a clear picture of these necessities, examine your discretionary spending. This might include dining out, entertainment, and subscriptions. Prioritize cutting back in these areas to free up funds for debt repayment. Consider using tools like budgeting apps or spreadsheets to track and categorize every dollar. By systematically organizing your expenses, you’ll have a clear roadmap to allocate more towards paying off debts while maintaining essential family needs.
Create a Realistic Debt Repayment Plan
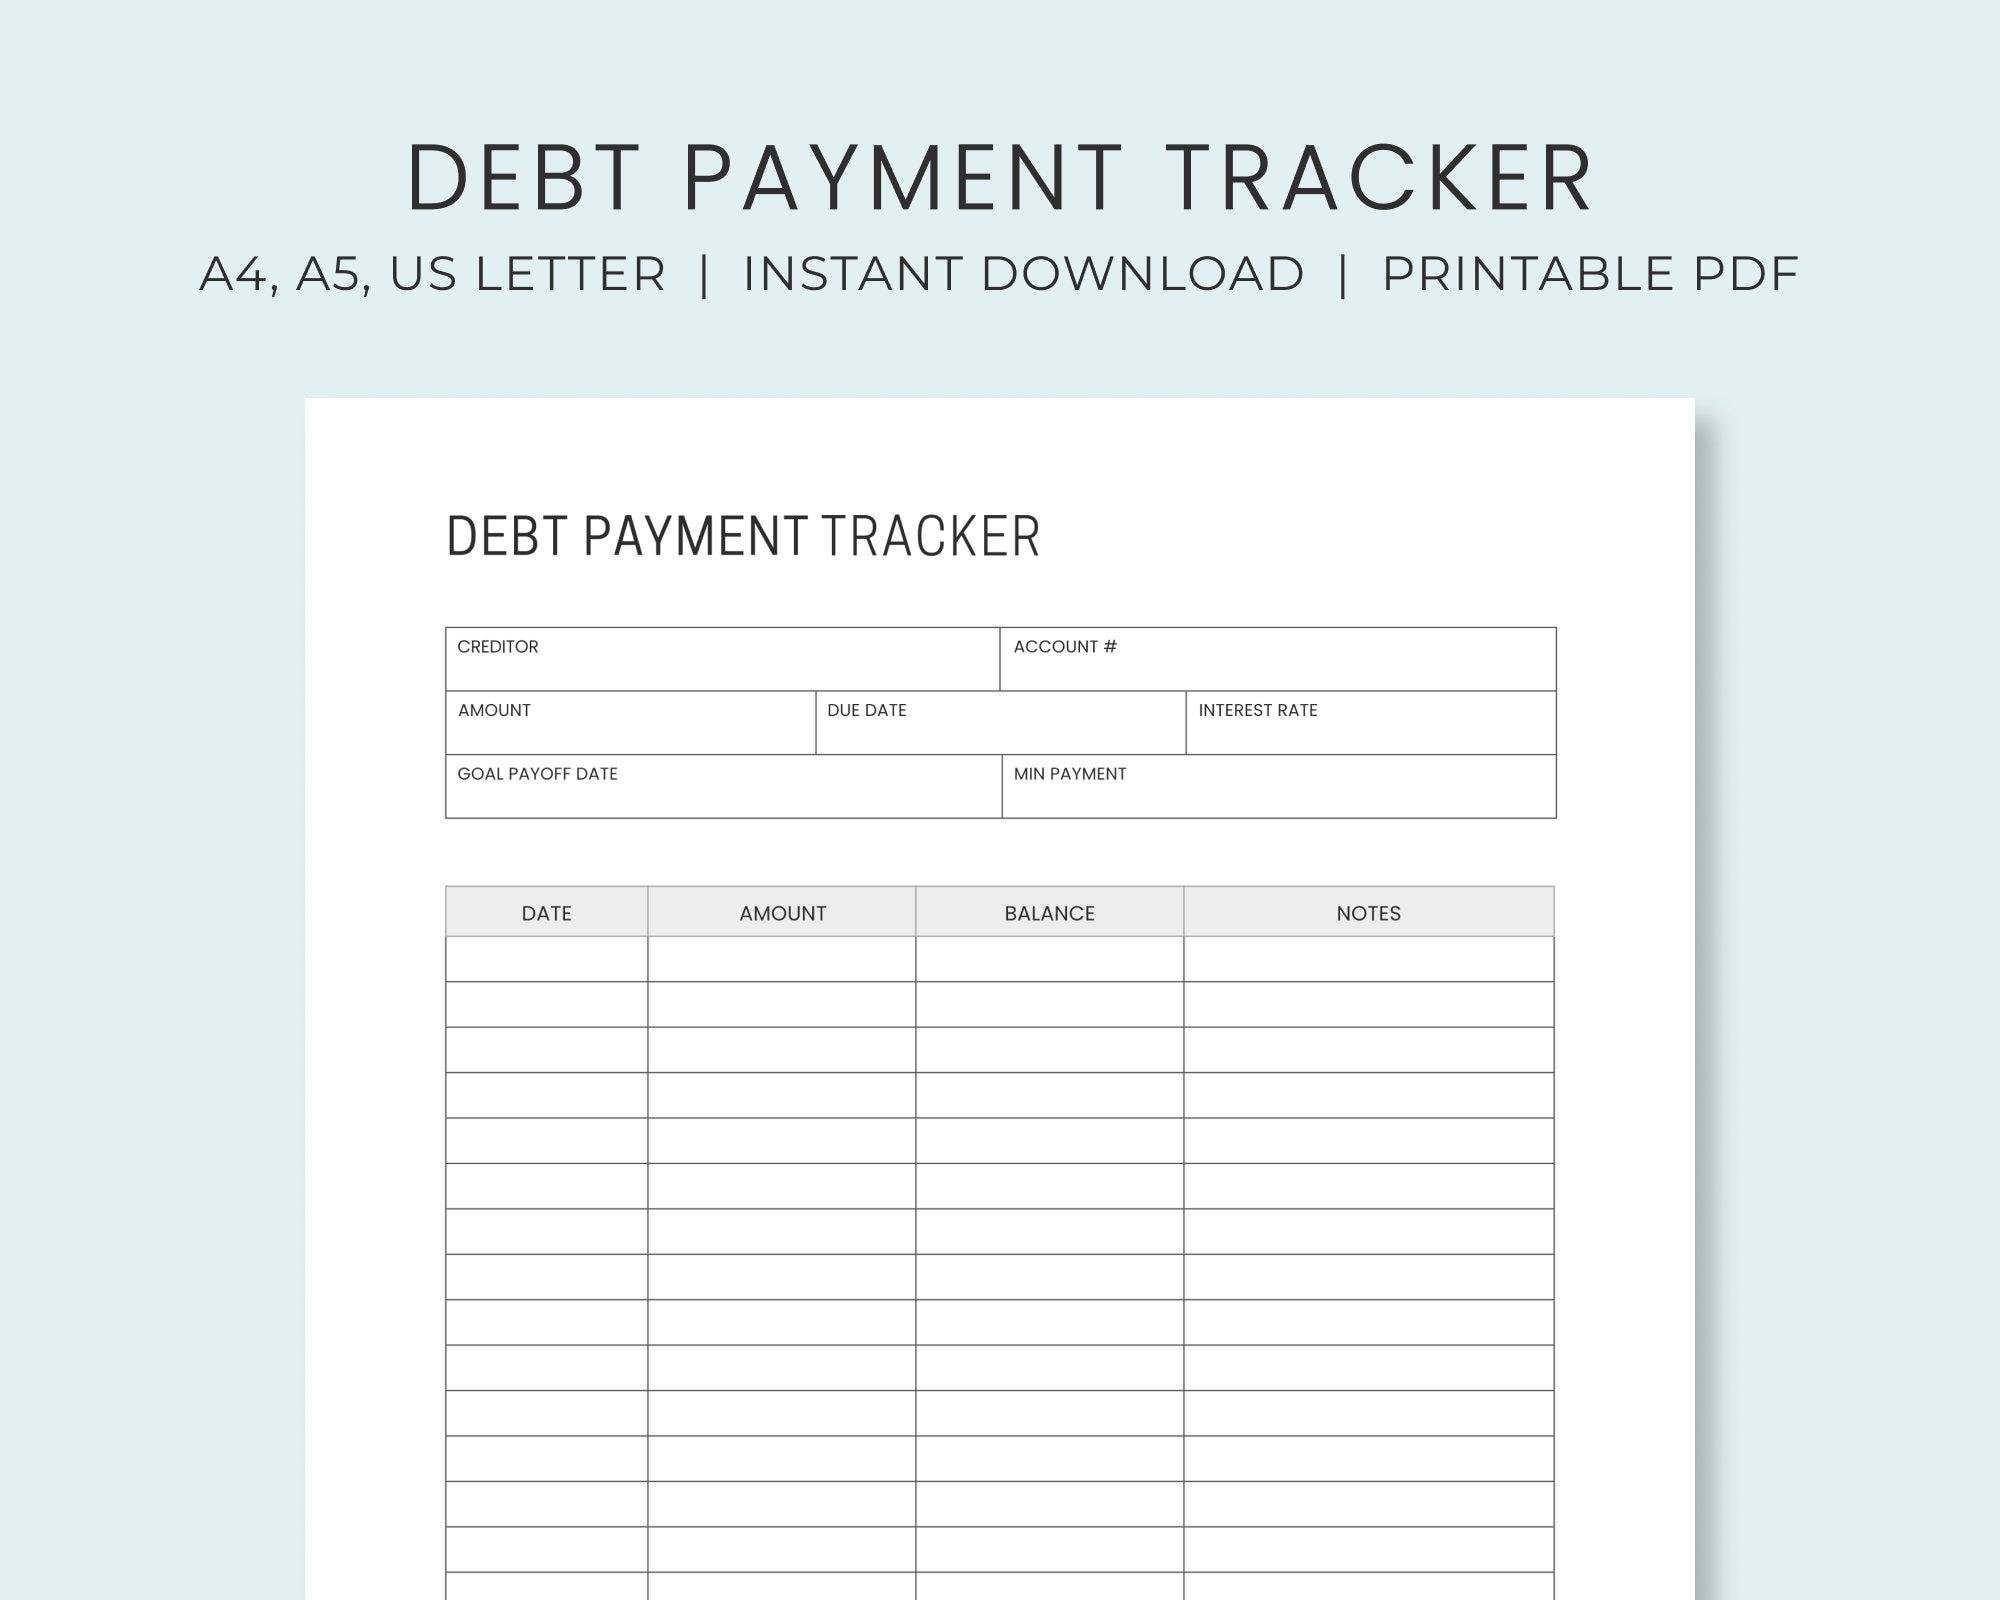
To tackle debt effectively, it’s essential to craft a plan that’s both realistic and sustainable for your family. Start by assessing your total debt, breaking it down into categories such as credit card balances, student loans, and mortgages. Prioritize these debts based on interest rates, from highest to lowest, to focus on minimizing the costliest liabilities first. Consider the avalanche method, where you pay off the highest interest debt first, or the snowball method, where you tackle the smallest debts to build momentum.
- List all debts with outstanding balances and interest rates.
- Decide on a fixed amount to allocate towards debt repayment each month.
- Cut unnecessary expenses to increase your repayment budget.
- Automate payments to avoid late fees and maintain consistency.
- Reassess and adjust your plan as debts are paid off or financial circumstances change.
Commit to this plan by integrating it into your family’s monthly budget. This ensures that debt repayment becomes a consistent part of your financial routine, helping you stay on track and ultimately achieving financial freedom.
Implement Strategies for Reducing Unnecessary Costs
To effectively manage your family budget with a focus on debt repayment, it’s crucial to pinpoint and eliminate unnecessary costs. Begin by scrutinizing your monthly expenses to identify non-essential items that can be reduced or eliminated. Dining out, subscription services, and impulse purchases often hide in plain sight, quietly draining your finances. Consider swapping these for cost-effective alternatives such as home-cooked meals, free trials, or simply prioritizing needs over wants.
Another powerful strategy is to renegotiate bills and seek discounts. Contact service providers like internet, phone, or insurance companies to explore better rates or promotions. Leverage your loyalty and commitment to these services as a bargaining chip for reduced rates. Additionally, opt for generic brands over premium ones, and buy in bulk for items you use regularly to enjoy savings in the long run. Implementing these strategies not only slashes unnecessary costs but also frees up more funds for debt repayment, accelerating your journey to financial freedom.
Monitor Progress and Adjust the Budget Regularly
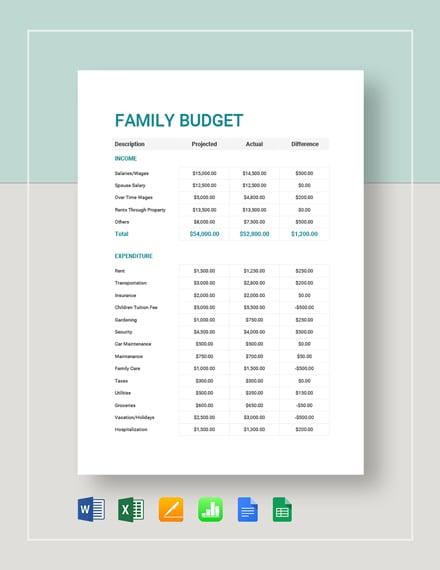
To ensure your family budget effectively supports your debt repayment goals, it’s crucial to keep a vigilant eye on your financial progress and make adjustments as needed. Regular monitoring allows you to identify areas where you might be overspending or where additional savings could be redirected toward debt reduction. Utilize budgeting apps or spreadsheets to track your spending and income, ensuring every dollar is accounted for and aligned with your repayment strategy.
Adaptability is key to maintaining a successful budget. Life is full of unexpected expenses, and being flexible will help you navigate these challenges without derailing your financial plans. Consider scheduling a monthly budget review session with your family. During these meetings, discuss:
- Recent changes in income or expenses
- Progress made toward debt repayment goals
- Adjustments needed to stay on track
- Opportunities for further cost-cutting or savings
By actively involving your family in these discussions, you create a supportive environment where everyone is committed to achieving financial freedom together.