
In today’s fast-paced financial landscape, managing debt effectively is more crucial than ever. Whether you’re grappling with student loans, credit card balances, or a hefty mortgage, the key to financial freedom lies in establishing a sustainable budget tailored to long-term debt repayment. This process, while seemingly daunting, can be navigated with confidence and precision. In this article, we will guide you through the essential steps to create a budget that not only addresses your current financial obligations but also sets you on a path toward a debt-free future. By understanding the fundamental principles of budgeting and implementing strategic financial practices, you can regain control over your finances and build a secure foundation for years to come. Let’s embark on this journey to financial stability together, equipped with the tools and knowledge to make informed and impactful decisions.
Understanding Your Debt and Setting Clear Goals
To effectively manage your debt, it’s crucial to gain a comprehensive understanding of what you owe. Start by gathering all your financial statements and create a detailed list of your debts. This list should include the total amount owed, interest rates, and minimum monthly payments. Knowing these details will give you a clear picture of your financial obligations and help you prioritize which debts to tackle first.
Once you have a firm grasp on your debt, it’s time to set clear, achievable goals. Consider the following steps to ensure your objectives are realistic and attainable:
- Prioritize high-interest debts to save money on interest over time.
- Set a timeline for each debt based on your income and expenses.
- Define milestones for reducing debt, such as paying off a certain amount each month.
- Adjust your budget to allocate more resources towards debt repayment without sacrificing essential needs.
By clearly understanding your debt and setting well-defined goals, you lay the groundwork for a sustainable budget that supports long-term debt repayment.
Crafting a Realistic and Flexible Budget Plan
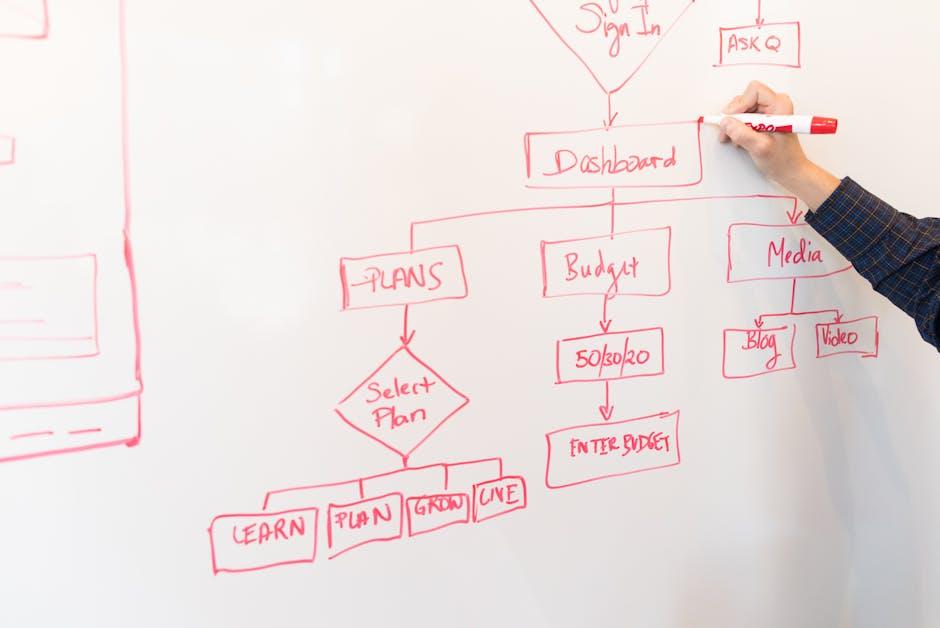
To effectively manage long-term debt repayment, it’s crucial to design a budget plan that is both realistic and adaptable. Start by identifying all your income sources and categorizing your expenses into fixed, variable, and discretionary. Fixed expenses are those that remain constant each month, such as rent or mortgage payments, while variable expenses might include groceries and utilities that can fluctuate. Discretionary spending involves non-essential items like dining out or entertainment. This categorization will help you pinpoint areas where you can cut back if necessary.
- Track Your Spending: Use apps or spreadsheets to monitor your expenses regularly. This helps in identifying patterns and adjusting your budget as needed.
- Prioritize Debt Repayment: Allocate a portion of your income specifically for debt repayment. Consider using methods like the avalanche or snowball approach to tackle debts strategically.
- Build an Emergency Fund: Set aside a small amount each month to build a cushion for unexpected expenses, ensuring that debt repayment stays on track.
Remember, flexibility is key. Revisit and adjust your budget monthly to reflect changes in income or expenses. By maintaining a clear overview of your financial landscape, you can stay committed to your long-term goals while adapting to life’s inevitable surprises.
Incorporating Savings and Emergency Funds into Your Budget
When working towards long-term debt repayment, integrating savings and an emergency fund into your budget is crucial for financial stability and peace of mind. Savings aren’t just about putting aside money for a rainy day; they’re an essential part of a well-rounded budget strategy that ensures you’re prepared for unexpected expenses. Start by allocating a small percentage of your income to a dedicated savings account. Even a modest contribution can accumulate over time and serve as a financial cushion. Consider the following strategies to boost your savings:
- Automate your savings to ensure consistency without the need for constant reminders.
- Redirect any windfalls or bonuses directly into your savings to accelerate growth.
- Regularly review and adjust your savings goals to reflect changes in your financial situation.
Equally important is the establishment of an emergency fund, which acts as a financial safety net in times of unforeseen circumstances, such as medical emergencies or sudden job loss. Aim to build a fund that covers three to six months of living expenses. This fund should be easily accessible yet separate from your regular savings to prevent unnecessary withdrawals. Consider these tips to build your emergency fund efficiently:
- Set up a high-yield savings account to maximize interest earnings on your emergency fund.
- Identify and eliminate non-essential expenses to funnel more money into your emergency fund.
- Reassess your emergency fund needs annually to ensure it aligns with your current lifestyle and obligations.
Monitoring Progress and Adjusting Strategies for Success
Regularly tracking your financial journey is essential to ensuring that your debt repayment plan remains effective. Begin by setting up a system to review your budget on a monthly or quarterly basis. This allows you to identify any discrepancies and adjust your strategy as needed. Utilize tools such as budgeting apps or spreadsheets to keep a detailed record of your income and expenses. Additionally, consider incorporating the following practices to enhance your progress:
- Set Milestones: Break down your debt repayment into manageable milestones. Celebrate each small victory to stay motivated.
- Evaluate Spending Habits: Regularly assess your spending patterns to pinpoint areas where you can cut back and redirect funds toward debt repayment.
- Adjust Payment Strategies: If your income increases or decreases, be prepared to adjust your payment strategies. Prioritize high-interest debts to minimize long-term costs.
By maintaining a flexible approach and staying informed about your financial status, you can adapt your budget to meet evolving circumstances and ensure that you remain on track for a debt-free future.