Navigating the labyrinth of medical bills can be a daunting task, especially when you’re managing a tight budget. With healthcare costs on the rise, it’s more important than ever to approach these expenses strategically and proactively. This article is designed to empower you with practical tools and proven strategies to tackle medical bills head-on without compromising your financial stability. Whether you’re dealing with unexpected emergencies or routine healthcare expenses, our guide will help you take control, prioritize your needs, and make informed decisions that safeguard both your health and your wallet. Let’s embark on this journey together and transform what seems like an overwhelming burden into a manageable part of your financial plan.
Understanding Your Medical Bills and Identifying Errors
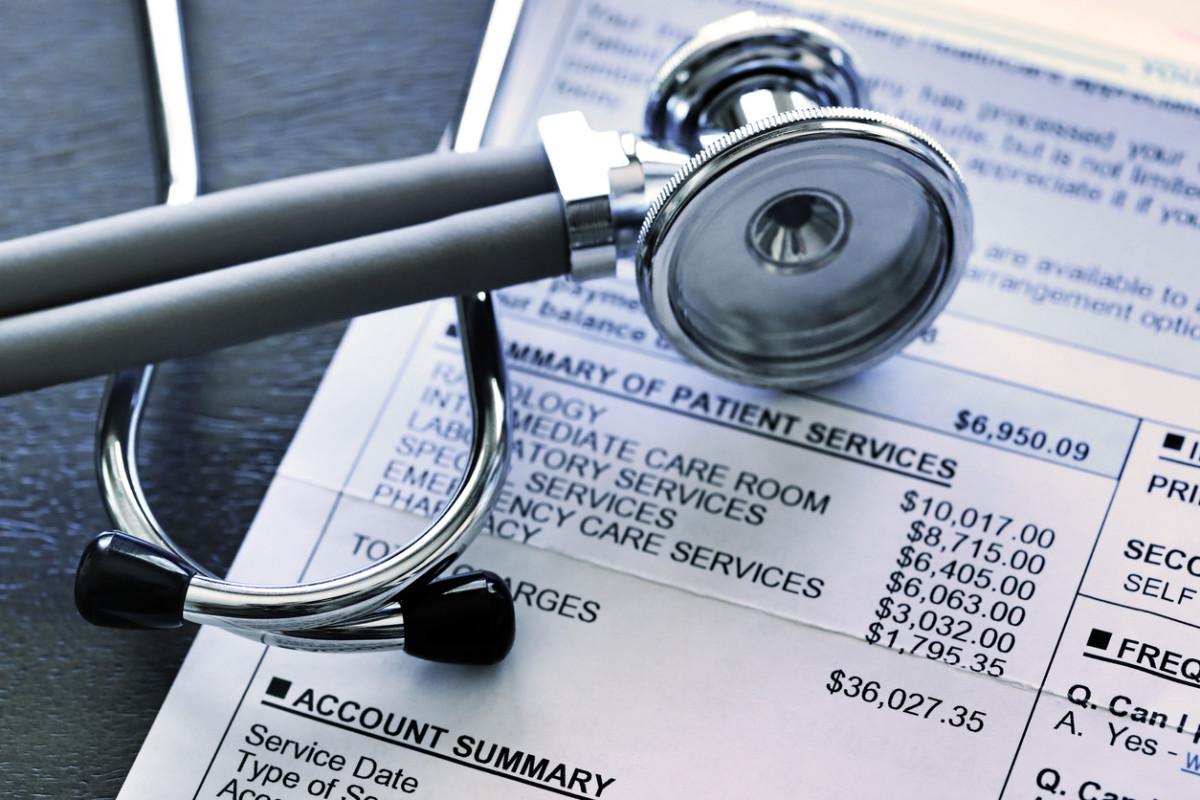
When you’re juggling a tight budget, every penny counts, and medical bills can quickly become overwhelming. It’s crucial to meticulously review each bill for accuracy, as errors are surprisingly common. Start by comparing your bills against your insurance statements and the explanation of benefits (EOB) provided by your insurer. Look for discrepancies such as incorrect billing codes, charges for services you didn’t receive, or incorrect patient information. These errors can significantly inflate your expenses.
- Verify the dates of service against your own records.
- Ensure that the billed services match what was provided during your visit.
- Check if your insurance was correctly applied and that you’re not being billed for services covered by your plan.
Should you spot any inconsistencies, reach out to your healthcare provider’s billing department promptly. Be assertive in your communications, providing detailed explanations of the errors you have identified. By taking these steps, you can ensure that you’re only paying for the care you actually received, helping to keep your medical expenses in check.
Prioritizing Medical Expenses and Setting a Realistic Budget
When navigating the labyrinth of medical expenses, it’s essential to first identify and prioritize your healthcare needs. Start by distinguishing between urgent and non-urgent medical services. Immediate needs, such as prescription medications or treatments for chronic conditions, should be at the top of your list. Routine check-ups and elective procedures, while important, can often be scheduled at a later date when your budget allows.
Once priorities are set, it’s time to craft a budget that reflects your financial reality. Begin by evaluating your monthly income and essential living costs. Subtract these from your total earnings to determine what remains for medical expenses. Consider implementing the following strategies to manage costs effectively:
- Negotiate with healthcare providers: Many are open to discussing payment plans or offering discounts.
- Explore generic medication options: These can significantly reduce pharmacy bills.
- Utilize preventive care services: Often covered by insurance, they can help avoid more costly treatments down the line.
- Review your insurance plan: Ensure it aligns with your current health needs and budget constraints.
Exploring Financial Assistance Programs and Negotiation Strategies
When you’re managing medical expenses on a tight budget, uncovering financial assistance programs can be a lifesaver. Start by researching hospital charity care programs and nonprofit organizations that offer financial aid. Many hospitals have dedicated funds to assist patients who cannot afford their bills. Additionally, government programs such as Medicaid or Children’s Health Insurance Program (CHIP) can provide substantial support. Don’t overlook local community health clinics that might offer services at reduced rates or on a sliding scale based on income.
Once you’ve explored assistance options, it’s time to engage in negotiation strategies. Begin by reviewing your medical bills meticulously for any errors. Contact the billing department to discuss any discrepancies and ask if they offer payment plans or discounts for upfront payments. Many providers are willing to negotiate the total amount due, especially if you can pay a portion of the bill immediately. Consider proposing a monthly payment plan that fits your budget, ensuring you’re clear about the terms to avoid any surprises. Remember, being proactive and assertive in your negotiations can often lead to significant reductions in your medical expenses.
Implementing Cost-Saving Measures and Preventing Future Debt
To alleviate the financial strain of medical bills, it’s essential to explore and implement various cost-saving measures. Begin by reviewing all medical statements for accuracy, ensuring that you are not being overcharged or billed for services not rendered. Engage in open dialogue with healthcare providers to negotiate bills, as many are willing to offer discounts or set up manageable payment plans. Don’t overlook the potential benefits of utilizing generic medications and exploring alternative treatment options that are often more cost-effective.
Preventing future debt is equally crucial, and this can be achieved by adopting a proactive approach to healthcare expenses. Consider enrolling in a Health Savings Account (HSA) or a Flexible Spending Account (FSA), which allow you to set aside pre-tax income for medical costs. Regularly review your insurance plan to ensure it aligns with your needs, and shop around during open enrollment for more affordable options. Additionally, prioritize preventative care to avoid costly treatments down the line. By adopting these strategies, you can maintain control over your finances and reduce the burden of medical expenses.