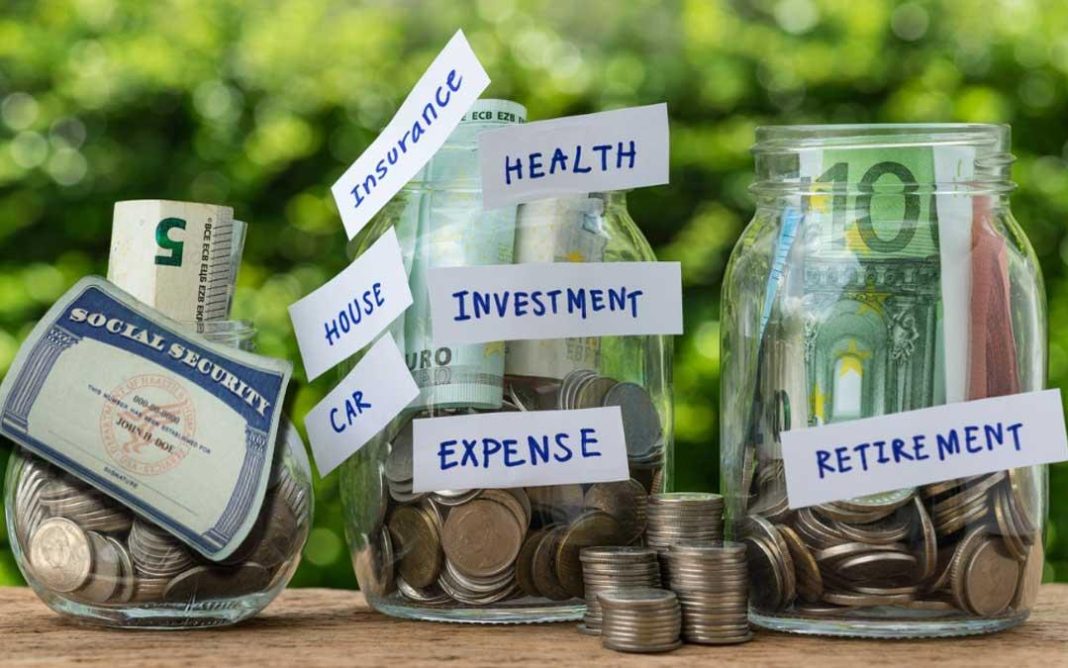

Managing debt while safeguarding your retirement savings can feel like walking a tightrope. Many individuals find themselves juggling financial obligations, wondering how to balance immediate debt repayment with long-term retirement goals. The good news is that with strategic planning and informed decision-making, it’s entirely possible to tackle debt without jeopardizing your future financial security. This guide will provide you with practical steps and expert advice to help you navigate this delicate balance, ensuring that you can effectively repay your debt while continuing to build a robust nest egg for your retirement. Let’s dive into actionable strategies that empower you to secure your financial present and future with confidence.
Prioritize High-Interest Debts to Minimize Financial Strain
One effective strategy to alleviate financial stress is to focus on clearing high-interest debts first. These debts, such as credit card balances and payday loans, often accumulate interest at a rapid pace, making them more expensive over time. By directing extra payments towards these liabilities, you can significantly reduce the total interest paid, freeing up resources for other financial goals. Consider the following steps to optimize this approach:
- Identify and list all your debts, categorizing them by interest rates.
- Prioritize payments on the highest interest debts, while maintaining minimum payments on others.
- Explore options such as balance transfers or consolidation loans to lower interest rates.
- Regularly review your progress and adjust your payment strategy as needed.
By systematically tackling these high-cost obligations, you not only reduce your financial burden but also create a more manageable path towards debt freedom without sacrificing your long-term retirement savings.
Leverage Budget Adjustments to Balance Debt Repayment and Savings
Achieving a harmonious balance between debt repayment and savings for retirement requires strategic budget adjustments. Begin by meticulously reviewing your current budget to identify areas where you can cut back without sacrificing quality of life. Small changes can have a big impact. Consider the following steps:
- Reevaluate recurring expenses: Subscriptions and memberships can often be trimmed or eliminated.
- Prioritize needs over wants: Focus on essentials and reduce discretionary spending.
- Optimize utility usage: Implement energy-saving practices to lower bills.
- Cook at home more often: Limit dining out to special occasions.
With the savings generated from these adjustments, allocate funds towards a dual-purpose financial strategy. Designate a portion for additional debt repayments, targeting high-interest obligations first, and channel the remainder into retirement accounts. This dual approach not only accelerates debt reduction but also ensures consistent growth in your retirement savings, safeguarding your future financial security. Remember, the key is consistency and discipline in adhering to your revised budget.
Utilize Employer Retirement Plan Benefits for Financial Flexibility
Maximizing the potential of your employer-sponsored retirement plan can be a game-changer in maintaining financial stability while tackling debt. Many employers offer plans such as 401(k)s or 403(b)s, which come with unique advantages that can be leveraged smartly. Consider the following strategies:
- Employer Matching Contributions: Ensure you contribute enough to receive the full employer match, as this is essentially free money that can bolster your retirement savings without additional out-of-pocket costs.
- Loan Options: Some retirement plans allow you to borrow against your savings at lower interest rates compared to personal loans. While this should be approached with caution, it can be a viable option if managed responsibly, ensuring you do not compromise your future security.
- Roth Contributions: If your plan offers a Roth option, take advantage of the tax-free growth potential. This can offer greater financial flexibility in retirement, allowing you to withdraw funds without tax implications.
By utilizing these features, you can maintain a balance between repaying debt and securing a comfortable retirement, ensuring that your financial future remains on track.
Seek Professional Financial Advice for Personalized Debt Solutions
When navigating the complex landscape of debt repayment while safeguarding your retirement nest egg, it’s crucial to understand that one-size-fits-all strategies may not work for everyone. Engaging a professional financial advisor can be a game-changer in crafting a debt repayment plan tailored to your unique financial situation. These experts can offer insights that go beyond generic advice, helping you balance debt reduction with the growth of your retirement savings. They assess your financial health comprehensively, considering factors such as income, expenses, existing debt, and retirement goals.
Financial advisors can provide a variety of personalized solutions, such as:
- Debt consolidation strategies that simplify your payments and potentially lower interest rates.
- Custom budgeting plans that align your monthly expenses with your debt and savings goals.
- Investment advice that ensures your retirement savings continue to grow, even while focusing on debt repayment.
- Negotiation assistance with creditors to explore options like interest rate reductions or adjusted payment terms.
By leveraging their expertise, you can make informed decisions that support both your immediate financial relief and long-term financial security.