Thursday, November 19, 2026
6.7 C
London

Best investment options for long term education savings accounts

In today’s ever-evolving financial landscape, planning for a child’s educational future is more crucial than ever. As tuition fees continue to rise, parents and guardians are increasingly seeking effective strategies to ensure that when the time comes, their children can access quality education without the burden of overwhelming debt. This article aims to guide you through the best investment options for long-term education savings accounts, equipping you with the knowledge and confidence to make informed decisions. From traditional savings plans to innovative investment vehicles, we will explore a variety of options tailored to meet diverse financial goals and risk appetites. By understanding the nuances of each option, you can craft a robust financial plan that not only secures your child’s educational aspirations but also aligns with your long-term financial objectives.
Understanding the Basics of <a href=Education Savings Accounts“>

Understanding the Basics of Education Savings Accounts

Education Savings Accounts (ESAs) are specialized investment tools designed to help parents and guardians save for future educational expenses. These accounts offer a variety of benefits, including tax advantages, which can make them a powerful option for long-term savings. Understanding the fundamental aspects of ESAs is crucial to maximize their potential.

  • Tax Benefits: Contributions to an ESA grow tax-free, and withdrawals for qualified educational expenses are also tax-free.
  • Flexibility: Funds can be used for a wide range of educational costs, from tuition to supplies, at both K-12 and higher education levels.
  • Contribution Limits: Be aware of the annual contribution limits and plan accordingly to maximize your savings potential.
  • Investment Options: ESAs offer diverse investment choices, allowing you to tailor your strategy based on your risk tolerance and financial goals.

By leveraging the benefits of ESAs, you can strategically plan for your child’s educational future while enjoying the advantages of tax-free growth and withdrawals. Making informed decisions about your contributions and investment choices will ensure that you are well-prepared to meet future educational expenses.
Exploring Tax-Advantaged Savings Options
Exploring Tax-Advantaged Savings Options

When it comes to saving for educational expenses, leveraging tax-advantaged accounts can make a significant difference. 529 Plans are a popular choice, offering tax-free growth and tax-free withdrawals for qualified educational expenses. Notably, some states even provide tax deductions or credits for contributions. Coverdell Education Savings Accounts (ESAs) also provide tax-free growth, though they come with contribution limits and income restrictions. Both of these options allow you to maximize your savings while enjoying favorable tax treatment.

Consider diversifying your strategy by exploring additional options such as:

  • Roth IRAs: While primarily a retirement account, Roth IRAs can be used to cover educational expenses without penalties, offering tax-free growth.
  • UGMA/UTMA Accounts: These custodial accounts provide flexibility, allowing funds to be used for any purpose, including education. However, they come with potential tax implications.

By carefully evaluating these choices, you can build a robust education savings strategy that aligns with your financial goals.

Diversifying Investments for Long-Term Growth

Diversifying Investments for Long-Term Growth

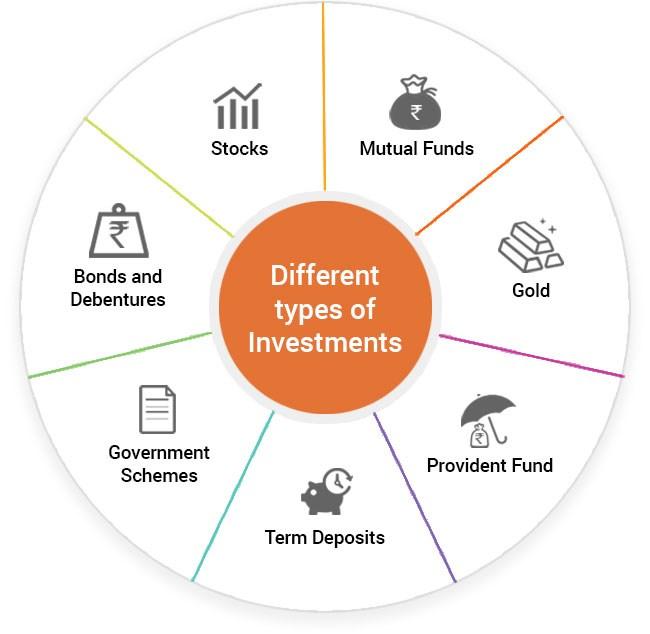
When planning for educational savings, it’s essential to consider a mix of diverse investment vehicles to maximize growth potential while managing risk. One approach is to explore a combination of index funds and mutual funds, which offer broad market exposure and professional management, respectively. These options typically provide a balanced mix of growth and income, which can be advantageous for long-term savings goals. For those comfortable with a bit more risk, stocks in high-growth sectors, such as technology or healthcare, may offer substantial returns over the years.

Additionally, incorporating bonds into your investment strategy can provide stability and consistent returns, particularly during market volatility. 529 Plans are another excellent choice, offering tax advantages and flexibility tailored specifically for educational expenses. Lastly, consider Exchange-Traded Funds (ETFs), which combine the diversification benefits of mutual funds with the flexibility of stock trading. By carefully selecting a blend of these options, you can build a robust and resilient portfolio aimed at securing educational financial needs in the future.

Choosing the Right Education Savings Plan for Your Needs

When planning for future educational expenses, it’s crucial to evaluate various savings plans to find one that aligns with your financial goals and circumstances. Start by considering a 529 College Savings Plan, which offers tax advantages and flexibility in how funds can be used across educational institutions. These plans are managed by states, and some even provide additional tax deductions or credits for contributions.

Alternatively, explore a Coverdell Education Savings Account (ESA), ideal for those wanting to save for both K-12 and higher education expenses. Though contributions are capped annually, they grow tax-free, providing significant long-term benefits. Here are a few key considerations when choosing the right plan:

  • Tax Benefits: Analyze the tax advantages each plan offers, both at the federal and state level.
  • Flexibility: Determine the range of educational expenses covered, from tuition to room and board.
  • Contribution Limits: Consider the maximum amount you can contribute annually without incurring penalties.
  • Investment Options: Look at the diversity of investment choices available within each plan to suit your risk tolerance.

By carefully examining these factors, you can select an education savings plan that not only supports your financial strategy but also ensures a brighter future for your loved ones.


Hot this week

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

Topics

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

How to Plan for Rising Costs During Retirement

To tackle rising costs in retirement, start by creating a detailed budget that accounts for inflation. Diversify your investment portfolio to hedge against market volatility, and consider healthcare savings plans to cover medical expenses.

Top Tips for Saving Money on Groceries Every Month

Cut costs with a meal plan: Plan weekly meals to avoid impulse buys. Buy in bulk for non-perishables, and choose generic brands. Use loyalty programs and coupons for extra savings. Shop with a list to stay focused and on budget.

How to Set Financial Goals That Work for Your Family

Setting financial goals for your family begins with open communication. Identify priorities, set realistic timelines, and track progress regularly. By aligning goals with family values, you create a plan that’s both motivating and achievable.
spot_img

Related Articles

Popular Categories

spot_imgspot_img