
In today’s fast-paced world, achieving financial stability and success as a family requires more than just good intentions—it demands a strategic approach. Setting time-bound financial goals is an essential practice that empowers families to navigate their financial journey with clarity and purpose. By establishing clear timelines, families can create a structured path to achieve their aspirations, whether it’s saving for a dream vacation, purchasing a new home, or securing a comfortable retirement. This article delves into the best practices for setting these time-bound financial goals, offering practical insights and actionable steps to ensure that your family’s financial future is not only well-planned but also attainable. With confidence and determination, you can transform your financial aspirations into reality, fostering a sense of accomplishment and security for your loved ones.
Establish Clear Time Frames for Achieving Family Financial Objectives
When aiming to achieve financial stability and growth for your family, establishing a clear timeline is crucial. Time frames act as milestones that keep everyone focused and motivated, ensuring that goals are not only set but also reached efficiently. To effectively set these time-bound objectives, consider the following approaches:
- Short-term Goals (0-1 year): These could include creating an emergency fund or saving for a family vacation. Quick wins help build momentum and confidence.
- Medium-term Goals (1-5 years): Examples include saving for a down payment on a house or paying off high-interest debt. These objectives require more planning and consistent effort.
- Long-term Goals (5+ years): Think about retirement savings or college funds for your children. These goals demand a strategic approach, often involving investments and regular contributions.
Integrating these timelines into your family’s financial planning not only fosters a disciplined approach but also makes it easier to track progress and make adjustments as necessary. Remember, the key is to remain flexible yet committed, adapting your strategies as life circumstances change while keeping your family’s ultimate financial aspirations in sight.
Develop a Strategic Plan to Align Family Financial Goals with Time Constraints
To effectively align your family’s financial goals with the time you have available, it’s crucial to develop a strategic plan that accounts for both immediate needs and long-term aspirations. Start by identifying each family member’s priorities and expectations. This process will help you set specific, measurable, achievable, relevant, and time-bound (SMART) goals that can guide your financial decisions. Communication is key—hold regular family meetings to ensure everyone is on the same page and adjust plans as necessary to accommodate any changes in circumstances.
Consider creating a flexible timeline that incorporates both short-term and long-term objectives. For instance, you might prioritize saving for a family vacation over the next year while simultaneously working towards a 5-year plan for purchasing a home. Break these goals into smaller, manageable tasks to prevent feeling overwhelmed. Here are some best practices to keep in mind:
- Set clear deadlines: Assign specific dates to each financial milestone to maintain momentum.
- Regularly review progress: Schedule monthly or quarterly check-ins to assess how well you are sticking to your plan.
- Be adaptable: Life is unpredictable, so be prepared to adjust your goals and timelines as necessary.
- Celebrate achievements: Recognize and reward your family for reaching key milestones to maintain motivation.
By following these strategies, you can create a dynamic financial plan that respects your family’s time constraints while moving you closer to your shared financial dreams.
Implement Monitoring Systems to Track Progress Toward Financial Milestones
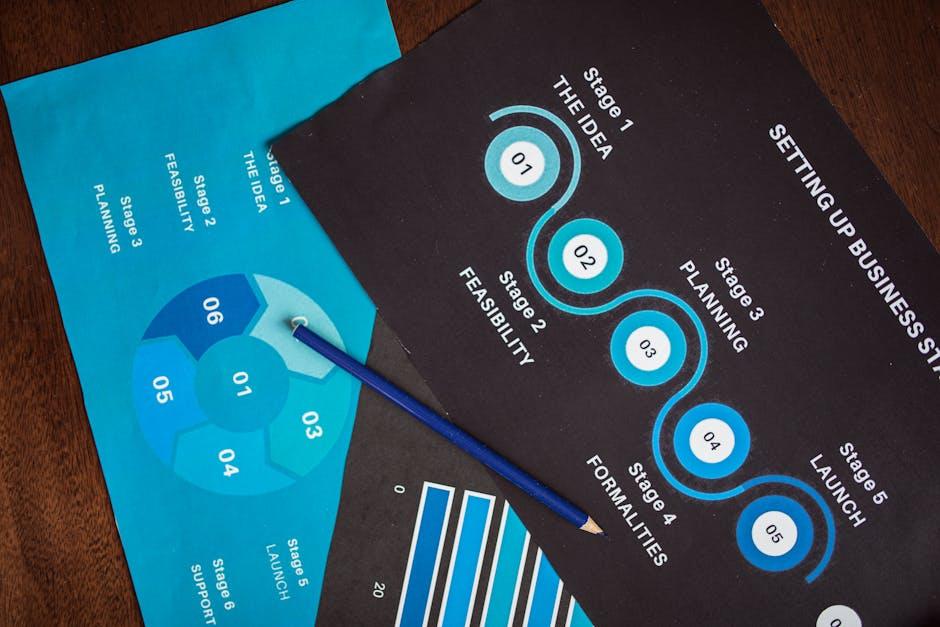
To ensure your family is on track to meet its financial aspirations, it’s crucial to establish effective monitoring systems. These systems not only help in tracking progress but also in making necessary adjustments to strategies when needed. Consider utilizing a mix of traditional and digital tools to keep a close eye on your progress. Budgeting apps can provide real-time updates on your expenses, while spreadsheets offer a customizable approach to tracking various financial metrics.
Moreover, setting up regular check-ins can be immensely beneficial. Create a schedule for monthly or quarterly family meetings to review financial goals and assess any changes in circumstances that might impact them. Use these sessions to analyze data, identify trends, and discuss potential improvements. By maintaining transparency and open communication, everyone stays informed and committed to the shared financial objectives.
Incorporate Flexibility to Adapt to Changing Family Financial Circumstances
Family financial landscapes can shift unexpectedly due to various factors such as job changes, unexpected expenses, or economic fluctuations. To ensure your financial goals remain relevant and achievable, it’s crucial to build in flexibility. Start by establishing a financial buffer. This could be an emergency fund that covers 3-6 months of living expenses, allowing you to stay on track even when surprises arise.
- Regularly review your financial goals and adjust them according to current circumstances.
- Prioritize goals based on urgency and importance, reallocating resources as needed.
- Consider diversifying income streams to reduce reliance on a single source.
- Communicate openly with family members about financial changes to align everyone’s expectations.
Incorporating these practices ensures that your financial planning is not only robust but also resilient, allowing your family to adapt seamlessly to any financial situation that comes your way.