
In today’s fast-paced world, securing your family’s financial future has never been more crucial. Whether you’re saving for your child’s education, planning for a dream vacation, or aiming for an early retirement, setting and achieving big financial goals can seem daunting. However, with the right strategies in place, these ambitions are not only attainable but can also be approached with confidence and clarity. This article will guide you through proven methods to navigate the complexities of financial planning, offering practical advice and actionable steps to ensure your family’s financial aspirations become a reality. From budgeting techniques to investment insights, we will equip you with the tools needed to transform your financial dreams into achievable milestones.
Setting Clear and Achievable Milestones
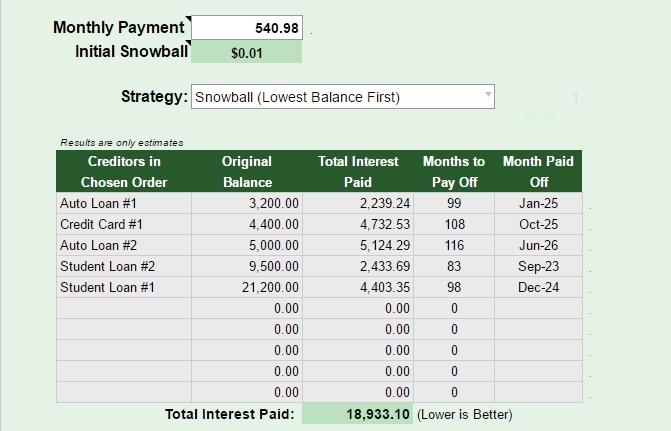
Breaking down your family’s big financial goals into smaller, clear, and achievable milestones is essential for maintaining momentum and motivation. Think of each milestone as a stepping stone that brings you closer to your ultimate financial dreams. To start, identify what each major goal entails and determine a realistic timeline for achieving it. This could mean setting quarterly savings targets or paying off a specific amount of debt by a certain date. Clarity in your milestones helps keep the entire family aligned and engaged in the process.
- Define Specific Milestones: Instead of saying, “We want to save for a house,” specify, “We will save $20,000 for a down payment in two years.”
- Prioritize Milestones: Focus on the most urgent financial goals first, such as building an emergency fund before saving for a vacation.
- Celebrate Achievements: Each milestone reached is a victory. Celebrate these achievements to boost morale and reinforce positive financial habits.
By , you create a roadmap that not only guides your family’s financial journey but also provides a sense of accomplishment and progress. With each milestone achieved, you’ll find renewed confidence in your ability to reach your family’s big financial goals.
Maximizing Savings with Smart Budgeting Techniques
Unlock the potential of your finances by implementing smart budgeting techniques that ensure every dollar works towards your family’s aspirations. Begin by crafting a comprehensive budget that accounts for both your fixed and variable expenses. This roadmap will help you identify areas where you can cut back and allocate more funds towards your goals. Remember, a successful budget isn’t just about restrictions; it’s about making informed decisions that bring you closer to your dreams.
- Track Spending: Use apps or spreadsheets to monitor where your money goes, helping you identify unnecessary expenses.
- Set Clear Priorities: Define what is most important to your family, whether it’s a new home, a vacation, or education, and focus your budget around these goals.
- Build an Emergency Fund: Protect your budget from unexpected expenses by setting aside a small amount each month.
- Automate Savings: Set up automatic transfers to savings accounts to ensure consistent contributions towards your financial targets.
- Review and Adjust: Regularly assess your budget to accommodate life changes and ensure it remains aligned with your objectives.
By embracing these techniques, you’ll not only foster financial discipline but also pave the way for achieving your family’s significant financial goals with confidence and efficiency.
Leveraging Investments for Long-Term Growth
Investing with a long-term perspective is a powerful strategy to secure your family’s financial future. By focusing on compound interest, you can exponentially grow your wealth over time. It’s essential to diversify your portfolio to mitigate risks and seize opportunities across different sectors. Consider the following strategies:
- Invest in Index Funds: These funds offer broad market exposure with lower fees, providing a reliable way to track the market’s overall growth.
- Reinvest Dividends: Use the power of compounding by reinvesting dividends to increase your stock holdings without additional capital.
- Embrace Dollar-Cost Averaging: Regularly invest a fixed amount regardless of market conditions, reducing the impact of volatility and fostering disciplined investing habits.
By strategically leveraging these investment avenues, you can create a robust financial foundation, positioning your family to achieve its most ambitious goals.
Utilizing Tax Advantages to Boost Your Financial Plan
Incorporating tax advantages into your financial strategy can significantly accelerate your progress towards achieving your family’s major financial milestones. Tax-advantaged accounts such as IRAs and 401(k)s not only provide a vehicle for retirement savings but also offer potential tax deductions that can enhance your current cash flow. Consider making the most of employer-sponsored retirement plans, especially if your employer offers matching contributions—this is essentially free money that can compound over time.
- Utilize Flexible Spending Accounts (FSAs): FSAs allow you to use pre-tax dollars for medical expenses, effectively lowering your taxable income.
- Leverage Health Savings Accounts (HSAs): These accounts offer triple tax benefits: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are also tax-free.
- Maximize Education Savings with 529 Plans: Contributions grow tax-free, and withdrawals for qualified education expenses are tax-exempt, helping you save more efficiently for your children’s education.
By strategically utilizing these tax advantages, you can optimize your savings, minimize tax liabilities, and keep more of your hard-earned money working towards your family’s financial goals.