
In today’s fast-paced world, turning your family’s big dreams into reality requires more than just wishful thinking—it demands a well-structured financial strategy. Whether you’re aiming to buy a new home, fund your children’s education, or embark on that once-in-a-lifetime family vacation, creating a robust savings plan is the cornerstone of achieving these goals. This guide will walk you through the essential steps to establish a savings plan tailored to your family’s aspirations, empowering you to confidently navigate your financial future. By taking control of your finances today, you set the stage for a tomorrow filled with opportunities and fulfilled dreams. Let’s embark on this journey together, transforming hopes into actionable plans and ensuring your family’s dreams are within reach.
Identifying Your Familys Big Dreams
Embarking on a journey to fulfill your family’s aspirations starts with clearly identifying what those dreams are. Begin by gathering your loved ones and engaging in an open dialogue about the goals you each hold dear. This conversation is crucial, as it allows everyone to voice their hopes and desires, ensuring a shared vision. To facilitate this discussion, consider asking each family member to share their top dreams. These might include:
- Buying a new home
- Embarking on a memorable family vacation
- Funding higher education for children
- Starting a family business
- Planning for early retirement
Once you have a comprehensive list, prioritize these dreams based on their significance and feasibility. This prioritization will guide your savings plan, focusing your efforts on the most impactful goals first. Use tools like vision boards or digital planners to keep these dreams visible and top-of-mind, reinforcing the collective motivation to turn them into reality. With a clear understanding of your family’s dreams, you’re now ready to map out a strategic savings plan to achieve them.
Setting Clear and Achievable Financial Goals
To set the stage for your family’s financial success, it’s crucial to outline goals that are both clear and achievable. Begin by identifying specific objectives that reflect your family’s aspirations. Whether it’s buying a new home, funding your children’s education, or planning a dream vacation, break down each goal into manageable steps. Consider the following aspects to ensure your goals are well-defined:
- Specificity: Clearly state what you want to achieve. Instead of a vague goal like “save money,” aim for something precise, such as “save $10,000 for a family vacation by next summer.”
- Measurability: Establish criteria to track your progress. Regularly check in on your savings milestones to ensure you’re on track.
- Attainability: Be realistic about what you can achieve given your current financial situation. Setting goals that stretch your abilities is fine, but they should still be within reach.
- Relevance: Ensure your goals align with your family’s values and long-term vision. This will keep everyone motivated and focused.
- Time-bound: Set a deadline for each goal. This adds urgency and helps prioritize tasks effectively.
By adhering to these principles, you create a roadmap that transforms your family’s big dreams into achievable milestones, guiding you steadily towards financial security and fulfillment.
Crafting a Realistic and Flexible Budget
When it comes to aligning your family’s financial aspirations with day-to-day spending, establishing a budget that adapts to life’s unpredictability is essential. Begin by distinguishing between your fixed and variable expenses. Fixed expenses include things like mortgage or rent, insurance, and loan payments—these remain constant each month. On the other hand, variable expenses such as groceries, entertainment, and dining out can fluctuate, offering opportunities for savings.
- Track Your Spending: Use budgeting apps or a simple spreadsheet to record every expense. This transparency helps you identify spending patterns and potential savings.
- Set Priorities: Determine what truly matters to your family. Is it a dream vacation, a new home, or college savings? Prioritize these goals in your budget.
- Allocate Funds Wisely: Allocate a portion of your income to a dedicated savings account for each goal. This strategy not only keeps your funds organized but also motivates you to stay committed.
Incorporate a buffer into your budget for unexpected expenses, ensuring that a surprise car repair or medical bill doesn’t derail your progress. By continuously revisiting and adjusting your budget, you create a dynamic tool that empowers your family to pursue big dreams without compromising financial stability.
Leveraging Savings Tools and Strategies
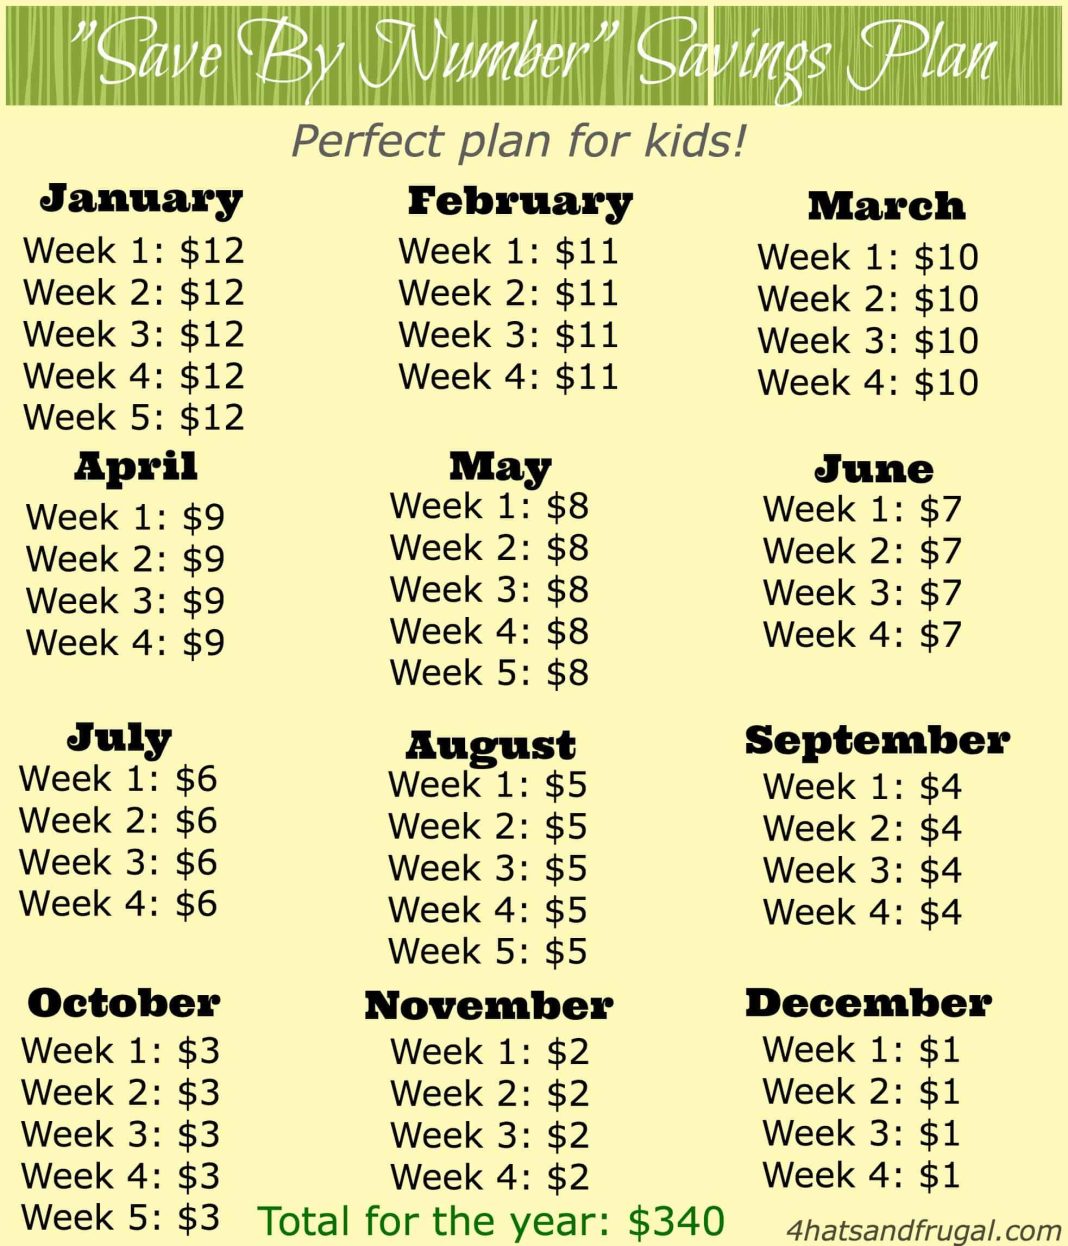
Transforming your family’s aspirations into reality requires smart financial maneuvering. By utilizing a mix of savings tools and strategies, you can effectively align your resources with your goals. Begin by exploring high-yield savings accounts, which offer better interest rates compared to traditional options. These accounts not only grow your savings faster but also ensure liquidity when you need access to your funds. Additionally, consider setting up automatic transfers to your savings account. This method minimizes the temptation to spend money meant for saving, turning it into a disciplined habit.
- Budgeting Apps: Use digital tools to track your expenses and identify areas for saving.
- Emergency Fund: Build a safety net to avoid dipping into your long-term savings for unexpected expenses.
- Certificates of Deposit (CDs): Lock in a portion of your savings at a higher interest rate for a fixed term.
- 401(k) and IRA Contributions: Don’t overlook retirement savings as part of your strategy. Maximize employer matches to grow your funds.
By strategically combining these tools, you can ensure that your family’s big dreams are supported by a robust financial foundation.