
In today’s fast-paced world, establishing a secure financial future for your family is more important than ever. With the myriad of expenses and financial responsibilities families face, having a clear and actionable plan is essential. Setting financial goals is not just about saving money; it’s about creating a roadmap that aligns with your family’s values and aspirations. This guide will walk you through the essential steps to identify, set, and achieve financial goals that will ensure stability and prosperity for your family. With the right strategies and commitment, you can turn your financial dreams into reality and secure a brighter future for your loved ones. Let’s embark on this journey together, equipping you with the knowledge and confidence to make informed financial decisions.
Identifying Your Familys Financial Priorities
Understanding what matters most to your family financially is a crucial step in setting meaningful goals. Start by having an open discussion with all family members about their individual and collective aspirations. Consider what aligns with your values and long-term vision. Here are a few questions to guide your conversation:
- What are our immediate needs and how do they compare to our future desires?
- Are we prioritizing education, retirement, or perhaps a dream vacation?
- How do unexpected expenses fit into our current financial landscape?
Once these priorities are identified, it’s essential to categorize them into short, medium, and long-term objectives. Short-term goals might include building an emergency fund or paying off a small debt, while long-term goals could be saving for a child’s college education or planning for retirement. By aligning your financial actions with these priorities, you can ensure that your family’s resources are directed towards what truly matters, paving the way for successful goal achievement.
Creating a Realistic and Actionable Budget Plan
Crafting a financial plan that aligns with your family’s aspirations begins with a realistic and actionable budget. Start by evaluating your current financial situation. Gather all financial documents, including pay stubs, bank statements, and bills. Once you have a clear picture, categorize your expenses into fixed and variable costs. Fixed costs might include mortgage or rent, utilities, and insurance, while variable costs could encompass groceries, entertainment, and dining out.
Next, establish financial goals that are specific, measurable, and time-bound. Here are some essential steps to consider:
- Prioritize Needs Over Wants: Ensure essential expenses are covered before allocating funds to discretionary spending.
- Set a Savings Target: Aim to save at least 20% of your income for emergencies and future investments.
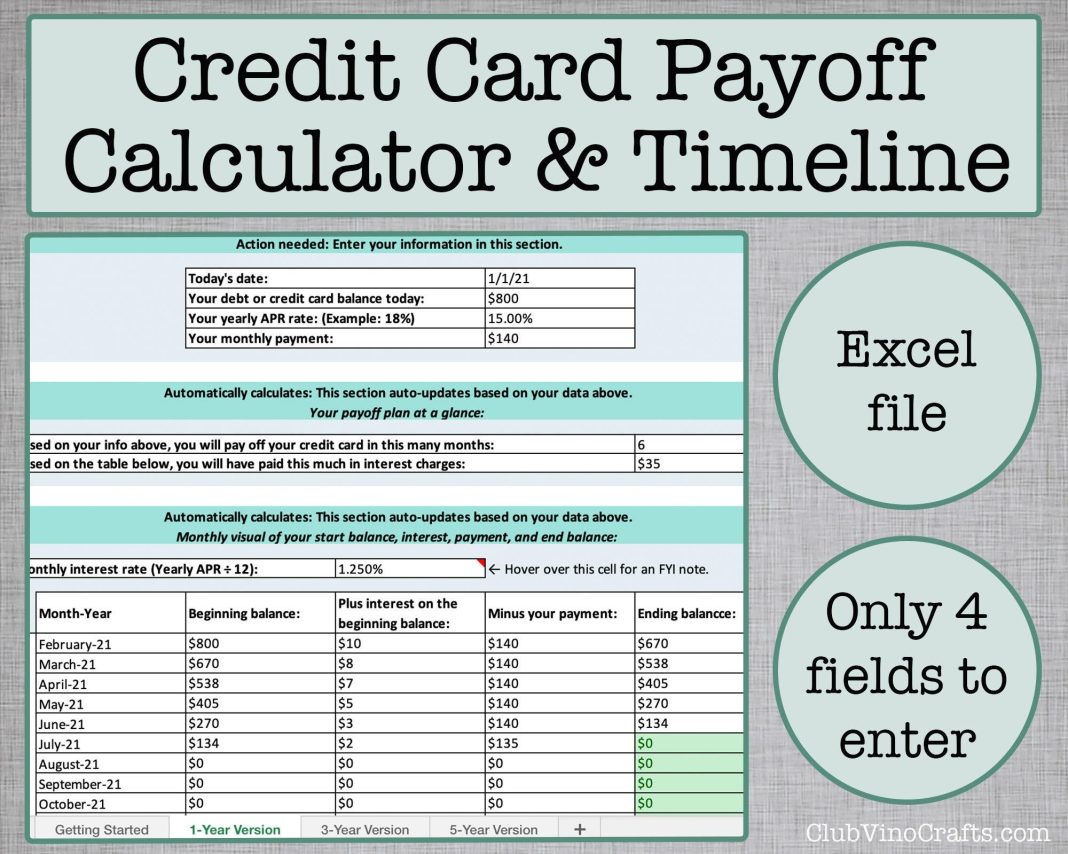
- Track Spending Habits: Use budgeting apps or spreadsheets to monitor where your money goes each month.
- Review and Adjust Regularly: Life changes, and so should your budget. Revisit your plan quarterly to make necessary adjustments.
By following these steps, you’ll create a budget that not only supports your current lifestyle but also sets the stage for achieving your family’s financial goals.
Building a Savings Strategy for Long-Term Security
Establishing a robust savings plan is crucial for ensuring long-term financial stability for your family. Start by assessing your current financial situation and identifying your family’s specific needs and aspirations. Set clear, realistic goals that encompass both short-term desires and long-term necessities. Think about milestones such as purchasing a home, funding your children’s education, or planning for retirement. Once you have a comprehensive list, prioritize them based on urgency and importance.
Implement a disciplined approach to savings by adopting these strategies:
- Automate Savings: Set up automatic transfers to your savings account to ensure consistent contributions.
- Emergency Fund: Build an emergency fund to cover unexpected expenses, targeting three to six months of living expenses.
- Regular Reviews: Schedule periodic reviews of your savings plan to adjust for changes in income, expenses, or financial goals.
By adhering to these strategies, you’ll cultivate a savings habit that supports your family’s financial well-being and future aspirations.
Monitoring Progress and Adjusting Goals for Continued Success
As you embark on your family’s financial journey, it’s essential to keep a vigilant eye on your progress and remain flexible with your goals. This dynamic approach ensures that you can swiftly navigate any unexpected financial challenges and seize new opportunities. Regularly reviewing your financial plan allows you to measure your progress against your goals and make necessary adjustments. Consider setting monthly or quarterly check-ins to evaluate your savings, investments, and expenses. During these reviews, ask yourself:
- Are we on track to meet our short-term and long-term financial goals?
- Have there been any significant changes in our income or expenses?
- Do we need to reallocate resources to different priorities?
Flexibility is key when adjusting your goals. Life is unpredictable, and your financial strategy should accommodate shifts in circumstances. If you find that a goal is no longer feasible or relevant, don’t hesitate to revise it. Similarly, if you’ve achieved a goal sooner than expected, set new, more ambitious targets to keep the momentum going. By maintaining this proactive approach, you ensure that your family’s financial plan remains robust and aligned with your evolving aspirations.