
Achieving your family’s financial dreams might seem like a daunting task, but with the right approach, it can be both manageable and rewarding. In today’s fast-paced world, financial security is more crucial than ever, yet many families find themselves unsure of where to start. This article will guide you through simple, effective steps to take control of your finances, set realistic goals, and steadily work towards the future you’ve always envisioned for your loved ones. Whether you’re saving for a new home, planning for your children’s education, or securing a comfortable retirement, these strategies will empower you to make informed decisions with confidence and clarity. Let’s embark on this journey together, turning aspirations into achievable milestones.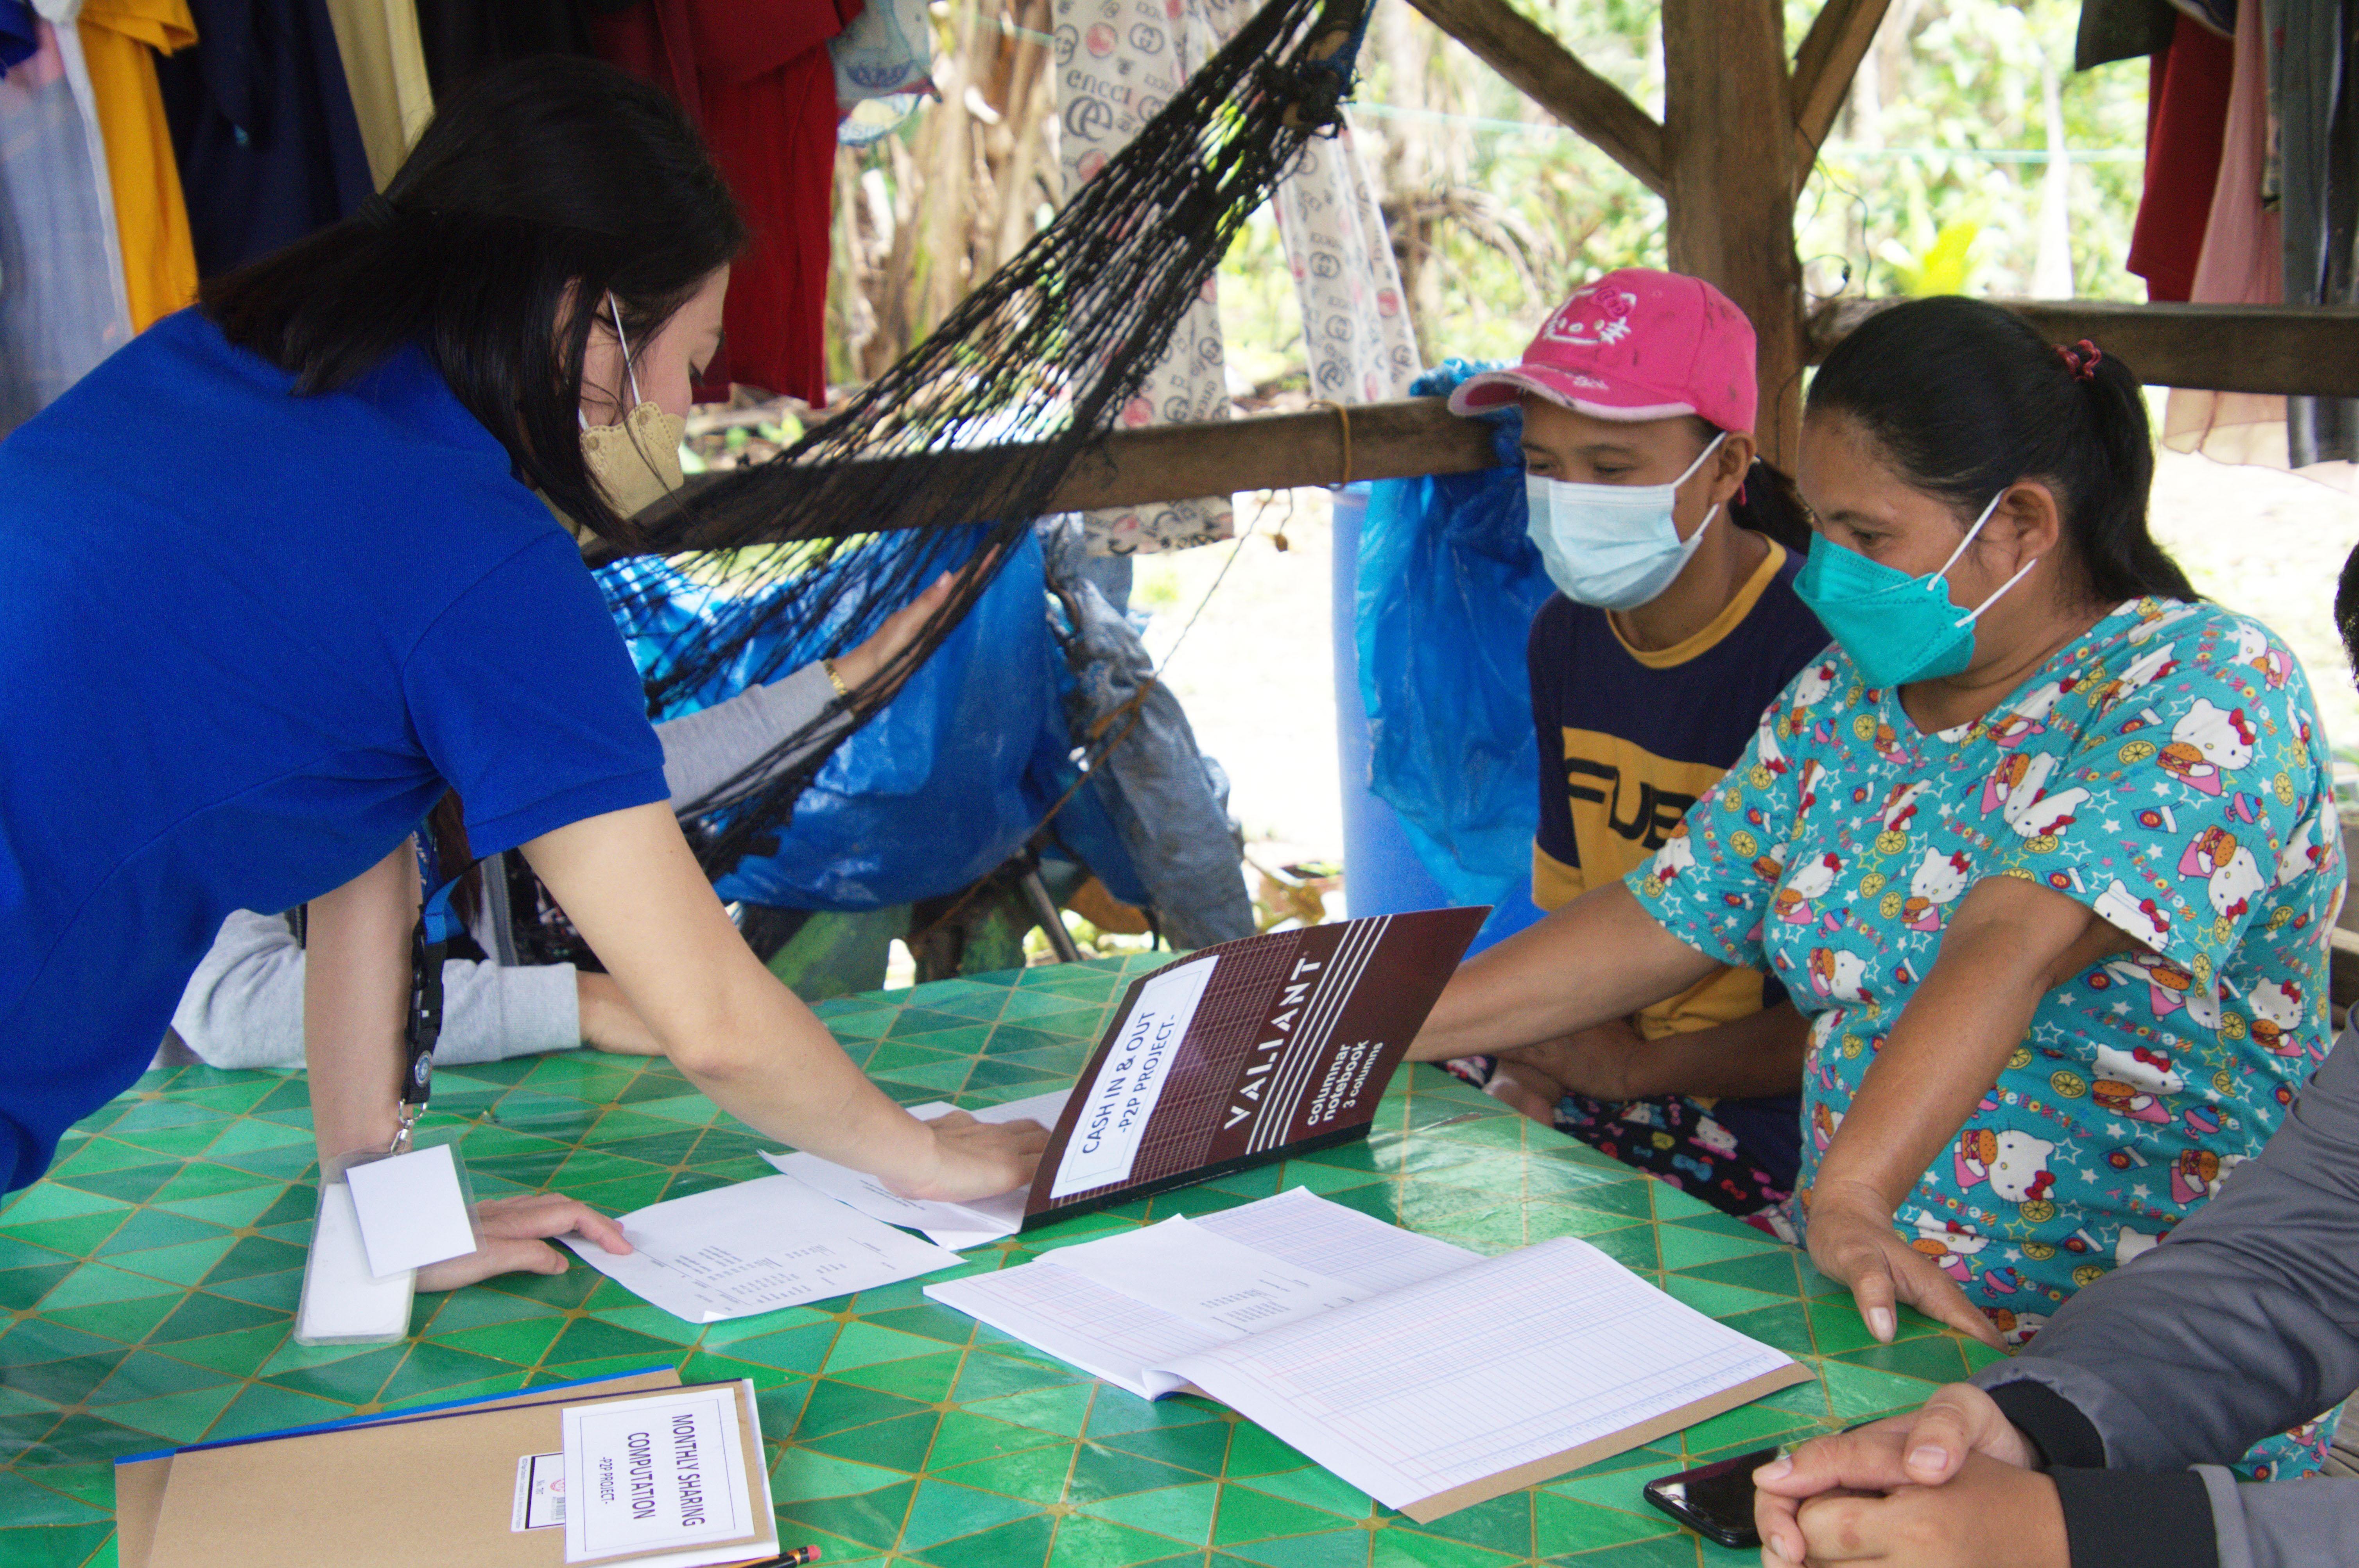
Creating a Solid Financial Foundation
To lay a strong groundwork for your family’s financial well-being, start by establishing a budget that aligns with your goals and values. Track your income and expenses diligently to identify areas where you can cut costs. Consider the following actions to boost your financial health:
- Set up an emergency fund: Aim for three to six months’ worth of living expenses to cushion against unforeseen events.
- Pay off high-interest debt: Focus on eliminating credit card debt and other loans with high-interest rates first.
- Invest in your future: Contribute regularly to retirement accounts, such as a 401(k) or IRA, to benefit from compound interest over time.
- Diversify income streams: Explore side hustles or passive income opportunities to increase financial security.
By implementing these strategies, you can create a robust financial foundation that supports your family’s dreams and ambitions. Remember, consistency and discipline are key to achieving long-term success.
Crafting a Realistic Family Budget
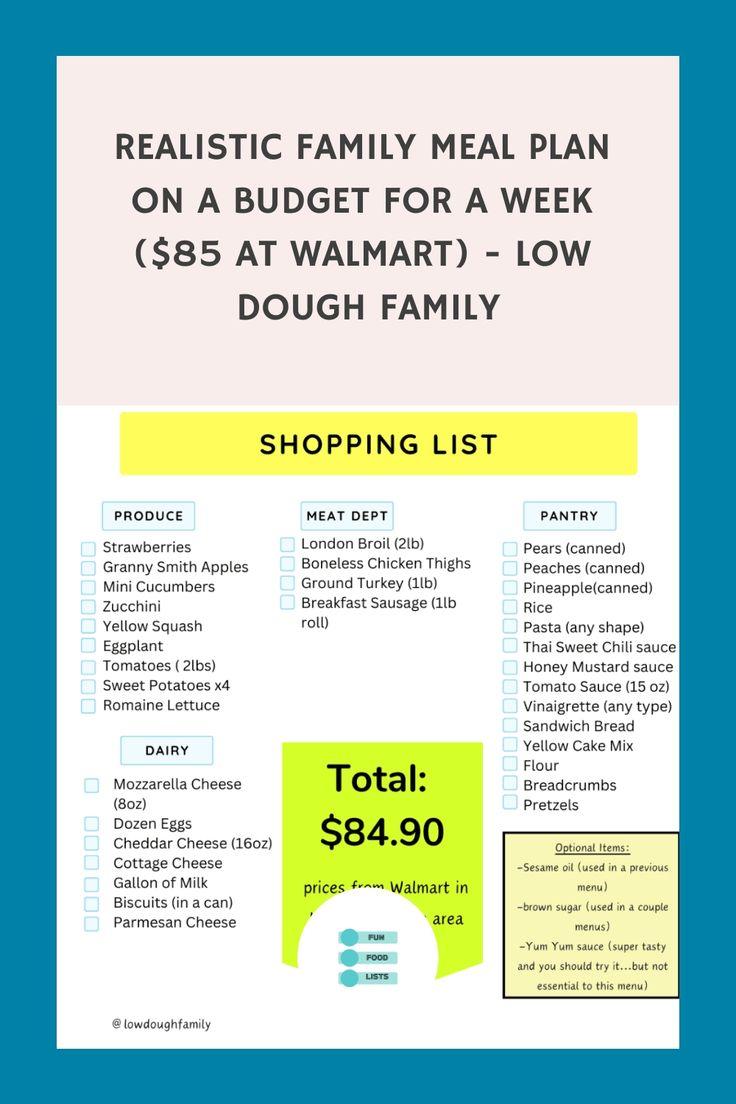
Developing a practical budget for your family begins with a thorough assessment of your income and expenses. Start by listing all sources of income, including salaries, bonuses, and any side hustles. Next, categorize your expenses into essential and non-essential items. Essential expenses typically include mortgage or rent, utilities, groceries, and insurance, while non-essential expenses might cover dining out, subscriptions, and entertainment. By clearly identifying these categories, you can make informed decisions about where adjustments might be necessary.
Once you have a clear picture of your financial landscape, prioritize savings and debt repayment. Consider implementing the following strategies:
- Automate savings: Set up automatic transfers to your savings account to ensure you’re consistently putting money aside for future goals.
- Track spending: Use budgeting apps or spreadsheets to monitor your daily expenses, helping you stay accountable and recognize spending patterns.
- Review and adjust: Regularly revisit your budget to account for any changes in income or expenses, ensuring it remains aligned with your financial aspirations.
By focusing on these steps, you’ll be well on your way to achieving your family’s financial dreams with confidence and clarity.
Investing Wisely for Future Goals
To achieve your family’s financial aspirations, it’s crucial to adopt a strategic approach. Start by clearly defining your financial goals, whether it’s buying a new home, securing your children’s education, or planning a dream vacation. Prioritize these goals based on urgency and importance. Once you’ve established your objectives, create a realistic budget that reflects your current financial situation and future ambitions. Consistency is key—ensure that you allocate funds regularly towards these goals, even if it’s a small amount. Remember, every little bit counts when you’re building a brighter financial future.
Consider diversifying your investments to minimize risk and maximize returns. Explore options such as stocks, bonds, and mutual funds, but ensure you understand each one’s potential risks and rewards. Consult with a financial advisor if needed to tailor an investment plan that aligns with your goals and risk tolerance. As you embark on this journey, regularly review and adjust your strategy to accommodate changes in your financial circumstances or market conditions. By taking these steps, you’ll be well on your way to turning your family’s financial dreams into reality.
Empowering Your Family with Financial Literacy
Embarking on the journey to achieve your family’s financial dreams starts with empowering every member with the right knowledge. Financial literacy is not just about managing money; it’s about understanding how to make money work for you. Here are some effective steps to get your family started:
- Set Clear Goals: Begin by discussing and setting short-term and long-term financial goals as a family. Whether it’s saving for a vacation, buying a new home, or planning for retirement, having clear objectives helps in creating a focused approach.
- Create a Family Budget: Involve everyone in crafting a budget that reflects your family’s priorities. This not only teaches accountability but also fosters a sense of teamwork.
- Educate on Financial Basics: Introduce fundamental concepts like saving, investing, and debt management. Consider fun and engaging methods such as games or apps designed to teach financial principles.
- Encourage Open Communication: Make financial discussions a regular part of family meetings. Encourage questions and share insights to ensure everyone is on the same page.
By integrating these steps into your family’s routine, you create a solid foundation of financial understanding that can pave the way to realizing your shared dreams. Remember, financial literacy is a journey, not a destination. Keep learning and growing together.