
In an ever-changing financial landscape, securing your family’s future requires more than just a steady income—it demands strategic planning and disciplined saving. As the cost of living continues to rise and unexpected expenses become the norm rather than the exception, it is crucial to adopt effective strategies that will safeguard your family’s financial well-being. This article aims to equip you with the top strategies for saving for your family’s future, offering practical guidance and actionable steps to build a robust financial foundation. Whether you’re just starting out or looking to optimize your current savings plan, these strategies will empower you to make informed decisions, ensuring peace of mind and financial security for the years ahead.
Building a Strong Financial Foundation for Your Family
Establishing a secure financial future for your family starts with strategic planning and disciplined saving. Begin by setting clear financial goals. Whether it’s a down payment for a home, college funds, or a retirement nest egg, having a defined target will guide your saving habits and provide motivation. Embrace the power of automated savings by setting up regular transfers to a dedicated savings account, ensuring that you consistently put money aside without the temptation to spend it elsewhere.
- Create a Budget: Track your income and expenses to identify areas where you can cut back and allocate more towards savings.
- Emergency Fund: Build an emergency fund covering 3-6 months of living expenses to protect against unexpected financial setbacks.
- Invest Wisely: Diversify your investments to grow your wealth over time, balancing risk and reward according to your family’s needs.
- Insurance Protection: Ensure you have adequate life and health insurance to safeguard your family’s financial stability.
Maximizing Savings Through Smart Budgeting Techniques
To secure a financially stable future for your family, it’s crucial to implement smart budgeting techniques. Begin by establishing a realistic budget that reflects your income and expenses. Regularly review and adjust this budget to account for any changes in your financial situation. It’s important to identify areas where you can cut back, such as dining out or subscription services, to increase your savings potential.
- Track your expenses: Use apps or spreadsheets to monitor where your money goes each month.
- Set clear savings goals: Define both short-term and long-term objectives to stay motivated.
- Automate savings: Set up automatic transfers to your savings account to ensure consistent contributions.
- Prioritize debt repayment: Focus on paying off high-interest debts to free up more money for savings.
- Review and adjust regularly: Make it a habit to evaluate your budget and savings plan monthly.
By adopting these strategies, you can make your money work harder for you, ensuring a secure financial future for your loved ones.

Investing Wisely to Secure Long-term Financial Growth
When it comes to ensuring your family’s financial well-being, adopting smart investment strategies is crucial. To pave the way for sustainable financial growth, consider diversifying your investment portfolio. Diversification helps in spreading risk across different asset classes, such as stocks, bonds, and real estate, thereby minimizing the impact of market volatility. Additionally, investing in index funds and exchange-traded funds (ETFs) can offer a balanced approach with lower fees, allowing you to benefit from the overall growth of the market without the need for constant monitoring.
Another key strategy is to establish a consistent saving habit. Automate your savings by setting up direct deposits into a dedicated savings account or investment fund. This ensures that you are consistently contributing to your financial goals without relying on willpower alone. Consider the following practical steps:
- Set clear, measurable financial goals for both the short and long term.
- Regularly review and adjust your investment strategy to align with life changes and market conditions.
- Educate yourself and stay informed about financial trends and opportunities.
By incorporating these strategies, you are more likely to achieve a robust financial foundation that supports your family’s future aspirations.
Utilizing Tax-Advantaged Accounts for Future Benefits
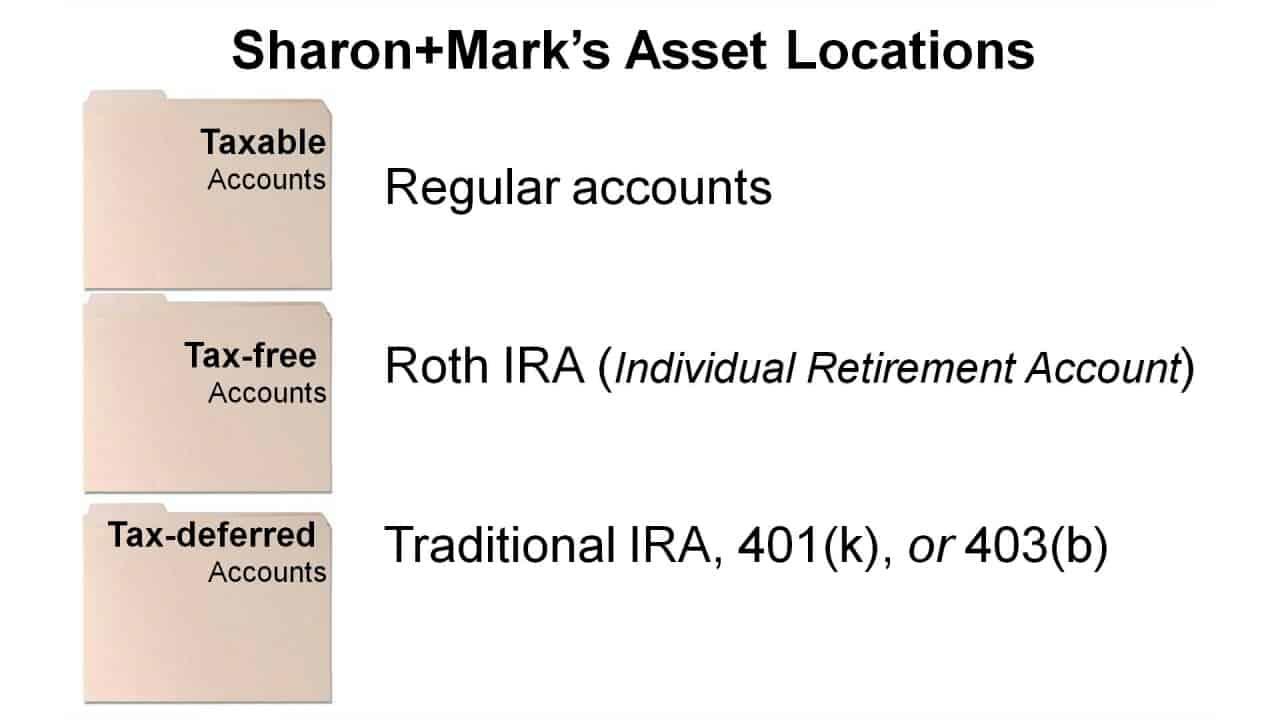
Maximizing the potential of tax-advantaged accounts can significantly boost your family’s financial security over time. These accounts offer unique benefits that allow your investments to grow more efficiently, thanks to tax deferment or tax-free earnings. 401(k)s, IRAs, and 529 plans are some of the most popular options available, each catering to different aspects of your financial planning. For instance, while 401(k)s and IRAs are geared towards retirement savings, 529 plans are designed to help you save for educational expenses.
Consider the following strategies to make the most of these accounts:
- Maximize Contributions: Aim to contribute the maximum allowed by law to your retirement accounts. This not only reduces your taxable income but also accelerates the growth of your investments.
- Leverage Employer Matches: If your employer offers a matching contribution to your 401(k), make sure to contribute enough to take full advantage of this benefit. It’s essentially free money added to your retirement savings.
- Diversify Investments: Use a mix of stocks, bonds, and other assets within your accounts to manage risk and enhance growth potential.
- Start Early: The earlier you start saving, the more you can benefit from the power of compound interest, which can exponentially increase your savings over time.
By strategically using these tax-advantaged accounts, you not only save on taxes today but also set the stage for a financially secure future for your family.