
As you approach retirement, a well-crafted strategy for minimizing taxes on your withdrawals can significantly enhance your financial security and ensure that your hard-earned savings last throughout your golden years. Understanding the intricacies of tax laws and leveraging them to your advantage can make a substantial difference in your retirement income. In this article, we will explore the best ways to reduce the tax burden on your retirement withdrawals, empowering you to make informed decisions and optimize your financial future. From strategic timing to selecting the right accounts, our comprehensive guide will provide you with the knowledge and tools needed to maximize your retirement funds while minimizing unnecessary tax liabilities.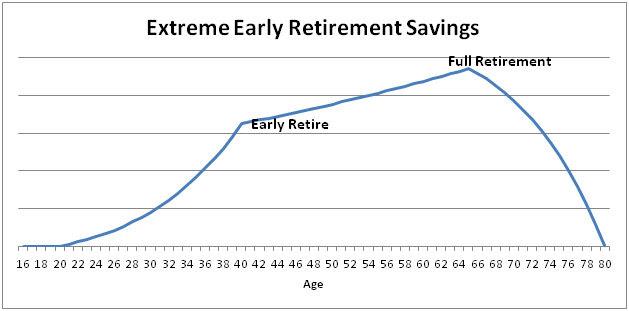
Optimize Your Withdrawal Strategy for Tax Efficiency
When it comes to ensuring tax efficiency in your retirement strategy, a well-thought-out withdrawal plan can make a significant difference. Strategically managing withdrawals from your various retirement accounts can help minimize the tax burden and extend the longevity of your savings. Consider these effective approaches:
- Prioritize Tax-Deferred Accounts: Begin by withdrawing from accounts like traditional IRAs or 401(k)s, where withdrawals are taxed as ordinary income. This can help manage your taxable income, especially if you’re in a lower tax bracket during retirement.
- Utilize Roth Accounts Wisely: Roth IRAs offer tax-free withdrawals. Leveraging these accounts later in retirement can be beneficial, particularly when you expect higher tax rates or want to manage Medicare premiums and Social Security taxes.
- Consider Required Minimum Distributions (RMDs): Failing to take RMDs can lead to hefty penalties. Plan ahead to ensure you’re withdrawing the required amounts from your tax-deferred accounts once you reach the age of 73 (or 72 if born before July 1, 1949).
- Balance Social Security and Pension Income: By carefully timing your Social Security benefits and pension withdrawals, you can optimize your overall tax situation. Delaying Social Security benefits can also increase your eventual payout.
By incorporating these strategies, you can effectively manage your retirement withdrawals and minimize taxes, ensuring that your nest egg lasts as long as you need it to.
Utilize Tax-Advantaged Accounts Wisely
Maximizing the benefits of tax-advantaged accounts is crucial for efficient retirement planning. These accounts, such as IRAs and 401(k)s, offer opportunities to reduce your tax burden both now and in the future. Start by contributing to a traditional IRA or 401(k), where you can deduct contributions from your taxable income, allowing your investments to grow tax-deferred. Alternatively, a Roth IRA or Roth 401(k) lets you make after-tax contributions, offering tax-free withdrawals in retirement.
- Understand Contribution Limits: Be aware of annual contribution limits and maximize them if possible. This not only boosts your retirement savings but also optimizes tax advantages.
- Consider Timing: Withdraw from tax-deferred accounts when your tax bracket is lower, such as early retirement years, to minimize taxes.
- Strategic Withdrawals: Balance withdrawals from different account types to maintain a favorable tax position. This can help in avoiding moving into a higher tax bracket.
Leverage Roth Conversions for Long-Term Savings
One strategic approach to minimize taxes on your retirement withdrawals is by converting a portion of your traditional IRA or 401(k) into a Roth IRA. This process, known as a Roth conversion, can be particularly beneficial for those who anticipate being in a higher tax bracket during retirement. By paying taxes on the converted amount now, you can potentially enjoy tax-free withdrawals later. This strategy can be especially advantageous if you expect tax rates to rise in the future or if you have years with lower taxable income, allowing you to convert at a lower tax rate.
Consider these key benefits of Roth conversions:
- Tax-Free Growth: Once in a Roth IRA, your investments grow tax-free, and qualified withdrawals are also tax-free.
- No Required Minimum Distributions (RMDs): Unlike traditional IRAs, Roth IRAs do not require you to take distributions at age 72, allowing your savings to grow uninterrupted.
- Estate Planning: Roth IRAs can be an effective tool for estate planning, as beneficiaries can inherit the account without the burden of paying taxes on distributions.
Before proceeding with a Roth conversion, consult with a financial advisor to ensure this strategy aligns with your long-term financial goals and tax situation.
Consider State Tax Implications in Your Retirement Plan
When planning for retirement, it’s crucial to recognize that state taxes can significantly impact your financial strategy. Each state has its own tax policies regarding retirement income, which can affect how much of your savings you get to keep. Researching and understanding the tax laws of your current or potential future state of residence is a vital step in minimizing your tax burden. Here are some strategies to consider:
- Relocate Wisely: Some states have no income tax or offer favorable tax treatments on retirement income. Consider relocating to a state that aligns with your financial goals.
- Diversify Income Sources: By having a mix of taxable, tax-deferred, and tax-free accounts, you can strategically withdraw funds to minimize your overall tax liability.
- Understand State-Specific Deductions and Exemptions: Familiarize yourself with state-specific deductions for retirement income, as some states offer exemptions on pensions, Social Security benefits, or other retirement distributions.
- Consult a Tax Professional: Engage with a knowledgeable tax advisor who can help tailor a plan that considers both federal and state tax implications, ensuring you maximize your retirement income.