
In the complex landscape of retirement planning, social security stands as a cornerstone of financial stability for millions of retirees. Understanding its role is crucial for anyone seeking to secure a comfortable and sustainable future. Social security is more than just a government benefit; it is a vital component of a comprehensive retirement strategy. With rising life expectancies and evolving economic conditions, the importance of integrating social security into retirement income planning has never been more significant. This article delves into the intricacies of social security, offering insights and guidance to help you maximize its potential benefits. Whether you’re on the brink of retirement or just beginning to plan, grasping the role of social security can empower you to make informed decisions that ensure financial security in your golden years.
Maximizing Your Social Security Benefits for a Secure Retirement
To effectively navigate the complexities of Social Security and secure a comfortable retirement, it’s crucial to understand how to maximize your benefits. Timing is everything: the age at which you choose to begin receiving Social Security benefits significantly impacts the amount you receive. By delaying benefits until the age of 70, you can increase your monthly payment by up to 8% per year beyond your full retirement age. This strategy can significantly boost your retirement income, offering greater financial security in your later years.
- Know your full retirement age (FRA): This is the age when you can start receiving full benefits, and it varies depending on your birth year.
- Consider spousal benefits: If you’re married, divorced, or widowed, you may be eligible for benefits based on your spouse’s record, which could be more advantageous than your own.
- Work history matters: Social Security benefits are calculated based on your highest 35 years of earnings. If you have less than 35 years of work, consider working additional years to maximize your benefits.
By understanding these key factors and strategically planning when and how to claim your benefits, you can optimize your Social Security income and enjoy a more secure retirement. Remember, knowledge is power, and informed decisions can lead to significant financial rewards.
Integrating Social Security into a Comprehensive Retirement Plan
When mapping out your retirement strategy, incorporating Social Security benefits can play a crucial role in ensuring a stable income stream. It’s essential to understand how these benefits fit into your broader financial landscape. Social Security is designed to replace a portion of your pre-retirement earnings based on your lifetime earnings record. However, it’s important to recognize that it is not intended to be your sole source of income during retirement. Instead, think of it as a foundational element that can be augmented by other income sources.
- Evaluate Your Benefits: Start by estimating your expected Social Security benefits using the SSA’s online tools. This will give you a clearer picture of what to expect and help you plan accordingly.
- Timing Matters: Consider the age at which you begin to claim benefits. Delaying benefits past your full retirement age can increase your monthly income, potentially providing more financial security in later years.
- Integrate with Other Income: Social Security should work in tandem with other retirement savings, such as 401(k) plans, IRAs, and pensions. Creating a balanced portfolio of income sources can help mitigate risks and provide a more reliable income stream.
By taking these steps, you can effectively weave Social Security into a comprehensive retirement plan that supports your long-term financial goals. Remember, careful planning and strategic decision-making are key to maximizing the benefits and ensuring a comfortable retirement.
Avoiding Common Mistakes in Social Security Income Strategy
Maximizing your Social Security benefits is a crucial part of retirement planning, yet many people fall into common traps that can significantly reduce their potential income. Understanding the impact of your claiming age is essential. Many individuals are unaware that claiming benefits as early as possible can lead to a permanent reduction in monthly income. Instead, consider delaying your claim to increase your benefits, especially if you anticipate a longer lifespan or have other income sources to rely on in the meantime.
- Overlooking spousal benefits: Couples often miss out on optimizing their combined benefits. Ensure you explore options like spousal or survivor benefits to maximize your household income.
- Failing to account for taxes: A portion of your Social Security benefits may be taxable depending on your overall income. Plan accordingly to avoid surprises during tax season.
- Ignoring inflation adjustments: Social Security provides cost-of-living adjustments, but they may not fully keep pace with inflation. Consider other income sources to maintain your purchasing power over time.
By steering clear of these pitfalls, you can ensure that your Social Security strategy is robust and contributes effectively to your overall retirement income plan.
Practical Steps to Enhance Your Social Security Income
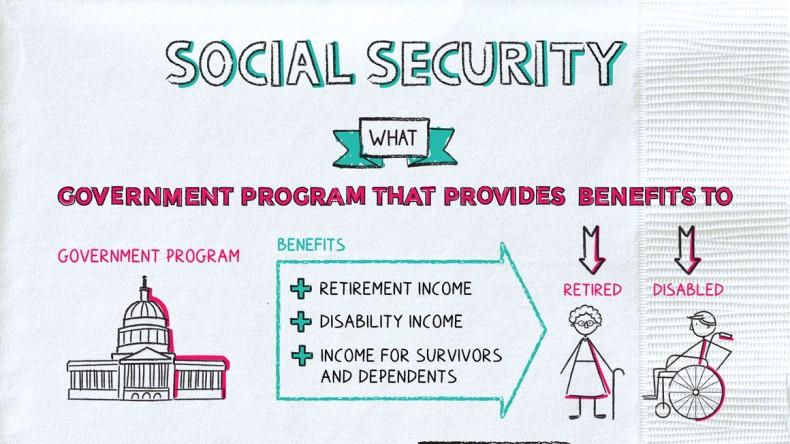
Maximizing your Social Security income involves strategic planning and informed decision-making. Here are some practical steps to ensure you make the most out of your benefits:
- Delay Claiming Benefits: One of the most effective strategies is to delay claiming your benefits. For each year you postpone receiving Social Security past your full retirement age up to age 70, your benefit increases by a certain percentage, often around 8% annually.
- Understand Spousal Benefits: If you’re married, take advantage of spousal benefits, which can be up to 50% of your spouse’s full retirement benefit. This can be particularly beneficial if one spouse had a significantly lower earning history.
- Work Longer: Continuing to work and increase your earnings can boost your Social Security benefits since they’re calculated based on your highest 35 years of earnings. Higher income years can replace lower-earning years, increasing your overall benefit.
- Monitor Your Earnings Record: Regularly check your Social Security statement to ensure your earnings have been accurately recorded. Mistakes can happen, and correcting them promptly is crucial for receiving the benefits you’re entitled to.
- Consider Tax Implications: Be mindful of how Social Security benefits can be taxed. Understanding your tax bracket and the thresholds for taxing Social Security can help you plan withdrawals from retirement accounts more strategically.