

In an era where financial stability is often threatened by unforeseen expenses and consumer temptations, mastering the art of planning for major purchases is not just prudent—it’s essential. Whether you’re eyeing a new car, a home renovation, or the latest tech gadget, the ability to make significant purchases without derailing your financial health is a skill that can lead to long-term economic success. This guide delves into strategic approaches to planning for major expenditures, ensuring that your financial goals remain intact while you acquire what you need or desire. By adhering to these expert-recommended strategies, you can confidently navigate the complexities of budgeting for large purchases, avoiding common pitfalls that lead to financial strain.
Establishing a Realistic Savings Timeline
To ensure your major purchases are financially manageable, it’s crucial to set a realistic timeline for your savings goals. Start by assessing your current financial situation, including income, expenses, and existing savings. Break down the total cost of your intended purchase into smaller, manageable chunks. This will help you determine how much you need to set aside each month.
- Evaluate Your Finances: Understand your cash flow and identify areas where you can cut back to free up funds for savings.
- Set Clear Goals: Define the exact amount needed for your purchase and by when you wish to achieve it.
- Create a Savings Schedule: Divide your goal into monthly savings targets, making it easier to track progress.
- Monitor and Adjust: Regularly review your progress and make necessary adjustments to stay on track.
By following these steps, you not only make your savings journey more achievable but also maintain control over your budget, ensuring financial stability while working towards your desired purchase.

Prioritizing Purchases Based on Necessity and Value
When it comes to major purchases, distinguishing between what is necessary and what merely adds value is crucial for financial stability. Start by evaluating the urgency of each item. Ask yourself: Is it something you need immediately, or can it wait? This will help you sort your list into categories that reflect your priorities. Additionally, consider the value each purchase brings to your life. Does it enhance your daily routine or solve a persistent problem? If an item scores high on both necessity and value, it deserves a spot at the top of your list.
- Immediate Needs: Focus on essentials like appliances or work-related tools that impact your daily life.
- Long-term Value: Consider investments that improve your home or health, providing benefits over time.
- Luxuries: Reserve these for when your budget allows, ensuring they don’t interfere with more pressing expenses.
By thoughtfully analyzing each potential purchase through the lens of necessity and value, you can make informed decisions that align with your financial goals and prevent budget overruns. Remember, a well-considered purchase today can lead to significant savings and satisfaction in the future.
Exploring Financing Options and Their Long-term Impact
When considering major purchases, it’s crucial to explore various financing options to ensure long-term financial health. Each option has distinct advantages and potential pitfalls. Personal loans often offer fixed interest rates and flexible repayment terms, making them a predictable choice for budgeting. However, they might come with higher interest rates compared to secured loans. Credit cards, while convenient, can lead to accumulating debt if not managed carefully. Opt for those with introductory 0% APR offers, but be wary of the terms once the promotional period ends.
Home equity loans and lines of credit (HELOCs) allow you to leverage your home’s value, often resulting in lower interest rates. Yet, they put your home at risk if payments aren’t met. Dealer financing for purchases like cars can be appealing due to promotional rates, but always read the fine print to avoid hidden fees. Consider these options:
- Personal Savings: Minimizes debt but may deplete emergency funds.
- Family Loans: Low interest but can strain relationships.
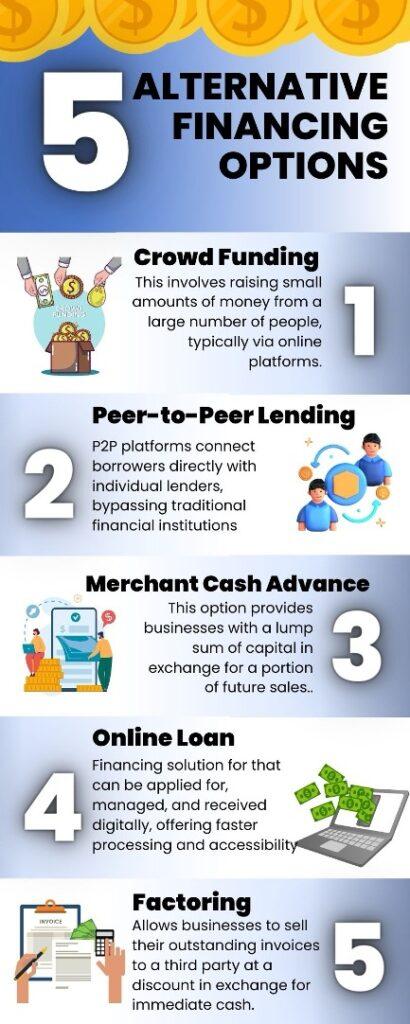
- Peer-to-Peer Lending: Flexible but variable interest rates.
Evaluating these options not only helps in making informed decisions but also safeguards against future financial strain. Always consider the long-term implications of each choice on your budget and financial goals.
Utilizing Budgeting Tools for Effective Financial Management
To make sure your major purchases don’t derail your financial stability, it’s crucial to leverage budgeting tools effectively. Start by identifying a budgeting tool that suits your lifestyle and financial habits, such as Mint, YNAB (You Need A Budget), or Personal Capital. These platforms can help you track expenses, set savings goals, and monitor your spending patterns.
When planning for significant expenses, consider the following strategies:
- Set Clear Goals: Define what you want to purchase and the timeline for achieving it. This clarity will help you allocate resources efficiently.
- Create a Dedicated Savings Plan: Use your budgeting tool to set aside a specific amount each month. Automate this process to ensure consistency.
- Track Your Progress: Regularly review your budget and adjust as needed. Look for spending areas where you can cut back to boost your savings.
- Forecast Future Expenses: Use your budgeting tool’s forecasting features to anticipate and prepare for upcoming financial needs.
By integrating these steps into your financial routine, you can make informed purchasing decisions without compromising your overall budget.




