
Raising children while planning for retirement can feel like a high-wire balancing act, where the stakes are your family’s future and financial security. Yet, with the right strategies and a proactive mindset, you can confidently navigate these dual responsibilities. In this guide, we will explore practical steps to harmonize the demands of parenting with the imperative of building a robust retirement plan. From budgeting techniques that accommodate both college savings and retirement funds, to investment strategies tailored for long-term growth, this article equips you with the knowledge and tools to secure your family’s financial well-being. Embrace the challenge with confidence, knowing that with careful planning, you can provide for your children today while ensuring a comfortable retirement tomorrow.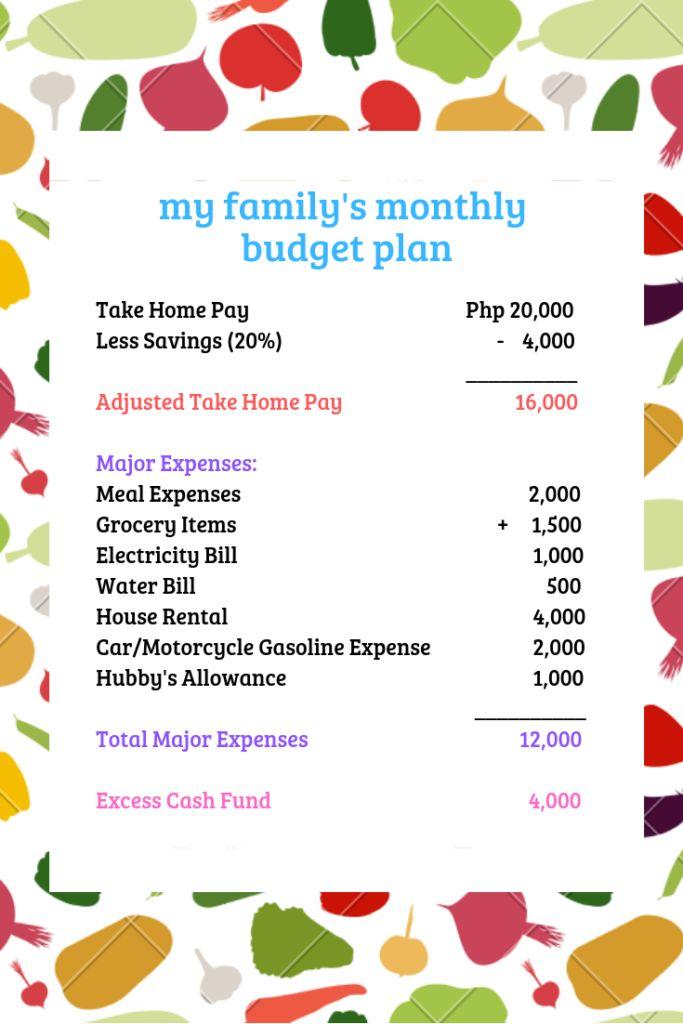
Balancing Family Expenses and Retirement Savings
Managing the delicate act of financing your children’s needs while ensuring a comfortable retirement can seem daunting, but it’s achievable with strategic planning. Begin by setting clear financial goals and prioritizing them. Start with an emergency fund to cover unforeseen expenses, which can prevent you from dipping into retirement savings prematurely. This financial cushion is crucial, especially when raising a family.
- Automate your savings: Set up automatic transfers to your retirement accounts to ensure consistent contributions.
- Educate your kids about money: Teach them the value of saving and budgeting, which can alleviate financial pressure in the long run.
- Review your budget regularly: Adjust your spending habits to reflect changes in family needs and financial goals.
Remember, it’s essential to strike a balance between enjoying the present with your family and securing your financial future. Leverage tax-advantaged accounts like 401(k)s or IRAs, which offer growth potential and tax benefits, aiding your retirement journey without compromising your family’s current needs.
Maximizing Tax-Advantaged Accounts for Future Security
To ensure a financially secure future while managing the expenses of raising children, it’s crucial to make the most of tax-advantaged accounts. These accounts can provide significant benefits if leveraged wisely. Consider the following strategies:
- Maximize Contributions: Aim to contribute the maximum allowable amount to accounts such as 401(k)s and IRAs. By doing so, you not only benefit from tax-deferred growth but also potentially lower your taxable income.
- Utilize a Roth IRA: If you qualify, a Roth IRA can be an excellent tool, offering tax-free growth and withdrawals in retirement. This can be particularly advantageous if you expect to be in a higher tax bracket in the future.
- Take Advantage of Employer Matching: Many employers offer matching contributions to 401(k) plans. Ensure you’re contributing enough to receive the full match, as this is essentially free money towards your retirement savings.
- Consider Health Savings Accounts (HSAs): If you have a high-deductible health plan, HSAs offer triple tax advantages: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are also tax-free. These can serve as a valuable resource in retirement.
By strategically utilizing these tax-advantaged accounts, you can build a robust financial foundation for your retirement, even as you navigate the costs of raising a family. Remember, each dollar saved today not only grows through compounding but also contributes to a more secure future.
Teaching Financial Literacy to Your Children
Empowering your children with financial literacy is a gift that will benefit them throughout their lives. Start by introducing them to basic financial concepts such as saving, budgeting, and spending wisely. You can create a fun and engaging environment by using games or apps designed for financial education. Encourage your children to set financial goals, like saving for a toy or a special outing, to instill the habit of goal-setting early on.
- Lead by Example: Show your children how you manage household finances, such as paying bills or setting aside money for savings.
- Open a Savings Account: Help them open a savings account and explain how interest works.
- Discuss Needs vs. Wants: Engage in conversations about distinguishing between needs and wants to foster mindful spending habits.
- Use Real-Life Scenarios: Involve them in budgeting for family trips or grocery shopping to give them practical experience.
By embedding these lessons into daily life, you’re not just teaching your children about money; you’re equipping them with essential skills for their future. As they grow, these foundational skills will help them understand more complex financial concepts, ultimately preparing them to make informed decisions in adulthood.
Creating a Sustainable Retirement Plan Amid Family Growth
Balancing the demands of family life with long-term financial goals requires strategic planning and a touch of creativity. Start by creating a comprehensive budget that accounts for both current expenses and future needs. This budget should include essentials like housing, food, and education, while also setting aside funds for retirement savings. Incorporate an emergency fund to cover unexpected expenses, ensuring that your retirement contributions remain uninterrupted.
- Prioritize savings: Allocate a percentage of your income to retirement accounts such as 401(k)s or IRAs.
- Invest in education funds: Use tax-advantaged accounts like 529 plans to save for your children’s education, easing future financial burdens.
- Review and adjust regularly: Life changes, and so should your financial plan. Reassess your budget and savings strategy annually.
- Involve the family: Teach your children about money management and involve them in budgeting discussions to foster a shared sense of financial responsibility.
By integrating these practices into your family routine, you can confidently navigate the complexities of raising children while securing a sustainable retirement future.