
In today’s fast-paced world, achieving financial stability is more important than ever, especially when it comes to securing your family’s future. Yet, setting financial goals that truly cater to your family’s unique needs can often feel overwhelming. This article is designed to cut through the confusion and empower you with practical strategies to craft financial goals that not only align with your family’s aspirations but also provide a clear path toward achieving them. Whether you’re saving for your children’s education, planning for a dream vacation, or building a robust emergency fund, understanding how to tailor financial goals to fit your family’s lifestyle and priorities is essential. Join us as we explore actionable steps and expert insights to help you confidently navigate the journey to financial success for your family.
Understanding Your Familys Financial Landscape
Before embarking on the journey to establish financial goals, it’s crucial to have a clear picture of your family’s financial landscape. Start by assessing your current financial situation. This includes evaluating your income, expenses, debts, and savings. Create a detailed budget that outlines your family’s monthly income sources and necessary expenses, such as housing, utilities, groceries, and transportation. Understanding these elements will provide a foundation for setting realistic and achievable goals.
Once you have a comprehensive view of your financial status, consider what your family’s short-term and long-term priorities are. These could include:
- Emergency Fund: Ensure that your family has a safety net for unexpected expenses.
- Debt Repayment: Focus on reducing high-interest debts to free up more resources for savings and investments.
- Education Savings: Plan for your children’s education costs, which may require a dedicated savings strategy.
- Retirement Planning: Start building a retirement fund that aligns with your desired lifestyle.
- Major Purchases: Set aside money for future major expenses, such as a home renovation or a family vacation.
Aligning your financial goals with your family’s values and priorities will make them more meaningful and attainable. Regularly review and adjust these goals as your family’s needs and circumstances evolve, ensuring they continue to serve your best interests.
Crafting Realistic and Achievable Financial Objectives
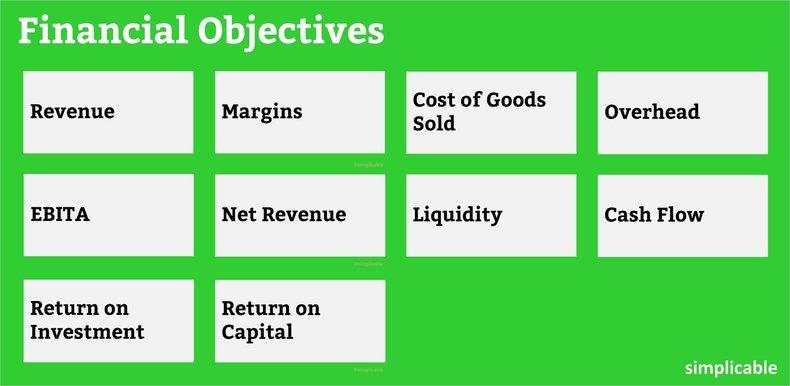
Creating financial objectives that truly resonate with your family’s lifestyle requires a blend of foresight and practicality. Start by assessing your current financial landscape, including income, expenses, and any existing debt. This will give you a clear picture of where you stand and help you identify areas for improvement. Once you have a solid understanding, prioritize your goals based on urgency and impact. Consider both short-term and long-term aspirations, such as building an emergency fund, saving for a family vacation, or planning for your children’s education.
- Define Clear Milestones: Break down larger goals into manageable steps. For instance, if your goal is to save $20,000 for a new car, set smaller milestones such as saving $500 each month.
- Align with Family Values: Ensure your financial goals reflect what’s truly important to your family. This might mean prioritizing experiences over material possessions or focusing on debt reduction.
- Regularly Review and Adjust: Life is unpredictable, and so is your financial situation. Schedule regular check-ins to assess your progress and make necessary adjustments to stay on track.
By grounding your financial goals in reality and aligning them with your family’s values, you can create a roadmap that not only supports your financial well-being but also enhances your overall quality of life.
Prioritizing Goals to Align with Family Values
When setting financial objectives, it’s crucial to ensure they reflect the core values your family holds dear. Start by gathering your family for a heartfelt discussion about what truly matters to each member. These conversations can help identify shared values, such as education, security, adventure, or philanthropy, which will serve as a compass in guiding your financial planning. By focusing on what is important, you can make informed decisions that strengthen family bonds and enhance your collective well-being.
Consider the following steps to align your goals with family values:
- Identify Key Values: Discuss as a family to pinpoint the values that resonate most with everyone.
- Set Value-Based Goals: Translate these values into specific, achievable goals that support them.
- Prioritize Together: Determine which goals should take precedence based on their alignment with your shared values.
- Review Regularly: Schedule regular family meetings to assess progress and make adjustments as necessary.
By following these steps, you not only ensure financial goals are met but also foster a sense of unity and purpose within your family.
Implementing a Plan for Consistent Financial Progress
Creating a roadmap for financial growth requires a strategic approach that is both disciplined and adaptable. Begin by evaluating your current financial standing and identify specific areas that require attention. This involves a thorough analysis of income streams, expenditure patterns, and potential savings opportunities. Once you have a clear picture, establish a realistic budget that aligns with your family’s priorities. Make sure to include an emergency fund to buffer against unexpected expenses.
To maintain momentum, consider implementing the following practices:
- Regular Financial Reviews: Schedule monthly check-ins to assess progress and adjust goals as necessary.
- Automate Savings: Set up automatic transfers to your savings account to ensure consistency without the temptation to spend.
- Invest in Education: Allocate resources towards financial literacy to empower informed decision-making.
- Set Short and Long-term Goals: Break down large financial objectives into manageable steps to track and celebrate achievements along the way.
By embracing these strategies, you can cultivate a sustainable financial environment that supports your family’s aspirations and provides peace of mind.