
In today’s unpredictable economic climate, establishing a robust family savings fund is not just a prudent financial decision—it’s a necessity. Whether you’re aiming to safeguard against unforeseen emergencies, save for future educational expenses, or plan for a well-deserved family vacation, a dedicated savings fund provides the security and peace of mind that every family deserves. This comprehensive guide will equip you with the essential strategies and tools needed to build a resilient family savings fund, ensuring that you can meet both expected and unexpected financial demands with confidence. By following these authoritative steps, you’ll be well on your way to creating a financial safety net that supports your family’s long-term goals and aspirations.
Establishing Clear Savings Goals and Timelines
Setting precise savings goals and defining timelines is crucial for a successful family savings fund. Begin by identifying what your family is saving for—be it a vacation, emergency fund, or college tuition. Next, determine the amount needed for each goal. Clarity in these objectives ensures everyone is on the same page and working towards the same target.
- Identify specific goals: Discuss with family members to outline what is important.
- Set a realistic timeline: Establish deadlines that are achievable and keep you motivated.
- Break down the savings target: Divide the total amount by the number of months until the deadline to determine monthly contributions.
Once your goals are set, use tools like spreadsheets or savings apps to track progress. Regularly reviewing these goals can help adjust timelines or contributions as necessary, ensuring your family stays on track. Remember, the key to successful savings is consistency and commitment.
Choosing the Right Savings Account and Investment Options
When building a family savings fund, it’s crucial to evaluate the financial tools available to you. Start by identifying a savings account that offers competitive interest rates and minimal fees. Look for features such as:
- No monthly maintenance fees
- ATM access for easy withdrawals
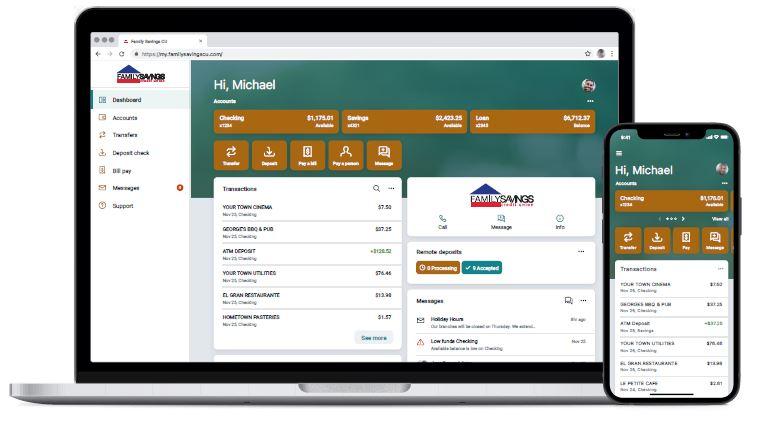
- Online banking capabilities for managing funds
- FDIC insurance for added security
Once you have a solid savings account, consider diversifying your portfolio with investment options that align with your family’s financial goals. Some popular choices include:
- Index funds for broad market exposure
- Bonds for more stable returns
- Real estate investments for potential long-term growth
- Mutual funds for professional management
By carefully selecting the right mix of savings and investments, you can effectively grow your family’s financial security over time.
Implementing Effective Budgeting Strategies for Consistent Contributions
To ensure your family savings fund grows consistently, adopting a robust budgeting strategy is paramount. Start by establishing clear savings goals that align with your family’s financial aspirations. Identify essential expenses and prioritize them, ensuring that discretionary spending is kept in check. It’s crucial to allocate a fixed percentage of your monthly income directly to your savings fund before addressing other financial commitments. This approach, often referred to as ‘paying yourself first,’ guarantees that your savings are prioritized.
Incorporate the following practices into your budgeting routine to enhance effectiveness:
- Automate Savings: Set up automatic transfers from your checking account to your savings account to enforce discipline.
- Review and Adjust: Regularly assess your budget to accommodate changes in income or unexpected expenses, ensuring consistent contributions.
- Involve the Family: Engage all family members in the budgeting process to promote transparency and collective responsibility.
- Utilize Budgeting Tools: Leverage digital tools and apps designed to track spending and facilitate better financial planning.
Monitoring Progress and Adjusting Plans for Long-term Success
Once your family savings fund is underway, it’s crucial to regularly evaluate your progress to ensure you’re on track to meet your goals. Begin by reviewing your savings contributions and the overall growth of your fund on a monthly or quarterly basis. This not only helps you stay informed but also provides an opportunity to celebrate small wins, reinforcing positive financial habits. Create a simple spreadsheet or use financial apps to track your savings, compare against your targets, and identify any discrepancies.
Adjusting your plans is equally important to accommodate changes in income, expenses, or family priorities. Consider these key steps:
- Reassess Goals: Periodically revisit your savings goals to ensure they align with your family’s evolving needs and aspirations.
- Adapt Contributions: If your financial situation changes, modify your savings contributions accordingly. Increase them during financially stable periods and scale back if necessary without derailing your long-term objectives.
- Evaluate Expenses: Regularly review your household budget to identify unnecessary expenses that can be redirected into your savings fund.
- Seek Professional Advice: Don’t hesitate to consult with a financial advisor for expert guidance tailored to your family’s unique circumstances.
By consistently monitoring and adjusting your approach, you can safeguard your family’s financial future and ensure your savings fund continues to grow effectively over time.