
In today’s rapidly changing financial landscape, building a robust family savings plan is not just a prudent choice—it’s an essential strategy for securing your family’s future. With the right approach, you can transform your savings into a dynamic financial foundation that grows and adapts over time, safeguarding against uncertainties and enabling long-term goals. This article serves as your comprehensive guide to constructing a family savings plan that not only meets your immediate needs but also thrives in the years to come. By integrating proven financial principles with practical steps, we will empower you to take control of your family’s financial destiny, ensuring stability and prosperity for generations. Dive in as we unravel the strategies and insights necessary to create a sustainable savings plan that stands the test of time.
Establishing a Strong Financial Foundation for Your Family
Creating a family savings plan that flourishes over time involves more than just setting aside money each month; it requires strategic planning and commitment. Start by clearly defining your family’s financial goals. Are you saving for a new home, your children’s education, or a comfortable retirement? Identify your priorities and set realistic, measurable goals. Once you have a clear picture, establish a budget that accounts for all your expenses, and identify areas where you can cut back. Allocate a fixed percentage of your income to savings, treating it as a non-negotiable expense. Consider setting up automatic transfers to your savings account to ensure consistency.
In addition to disciplined saving, explore ways to make your money work harder for you. Diversify your investments to include a mix of stocks, bonds, and mutual funds, taking into account your risk tolerance and investment horizon. Utilize tax-advantaged accounts like 401(k)s or IRAs to boost your savings. Regularly review and adjust your plan to stay on track with your financial goals. Keep your family involved in the process, teaching your children the importance of saving and financial responsibility. By implementing these strategies, you can build a robust financial foundation that supports your family’s aspirations and grows steadily over time.
- Define clear financial goals for short-term and long-term needs.
- Create a detailed budget to identify potential savings.
- Automate savings to ensure consistency and discipline.
- Diversify investments to balance risk and growth potential.
- Engage family members in financial planning to foster collective responsibility.
Strategic Budgeting Techniques to Maximize Savings Potential
Implementing strategic budgeting techniques is key to ensuring your family savings plan not only survives but thrives over time. Begin by establishing a clear understanding of your financial landscape. Assess your current income, expenditures, and financial obligations to determine a realistic savings target. This foundational knowledge will empower you to make informed decisions and prioritize your savings goals effectively.
To maximize your savings potential, consider the following strategic approaches:
- Zero-based budgeting: Allocate every dollar of your income to specific expenses, savings, or investments. This method ensures that your budget aligns with your financial priorities and prevents unnecessary spending.
- Envelope system: Use physical or digital envelopes to categorize your spending. This visual tool helps track and limit expenditures in each category, encouraging discipline and mindful spending.
- Automate savings: Set up automatic transfers from your checking account to your savings account. By treating savings as a non-negotiable expense, you’ll consistently contribute to your financial growth.
By integrating these techniques, you can build a robust family savings plan that not only meets immediate needs but also fosters long-term financial stability and growth.
Investing Wisely: Growing Your Family Savings Through Smart Choices
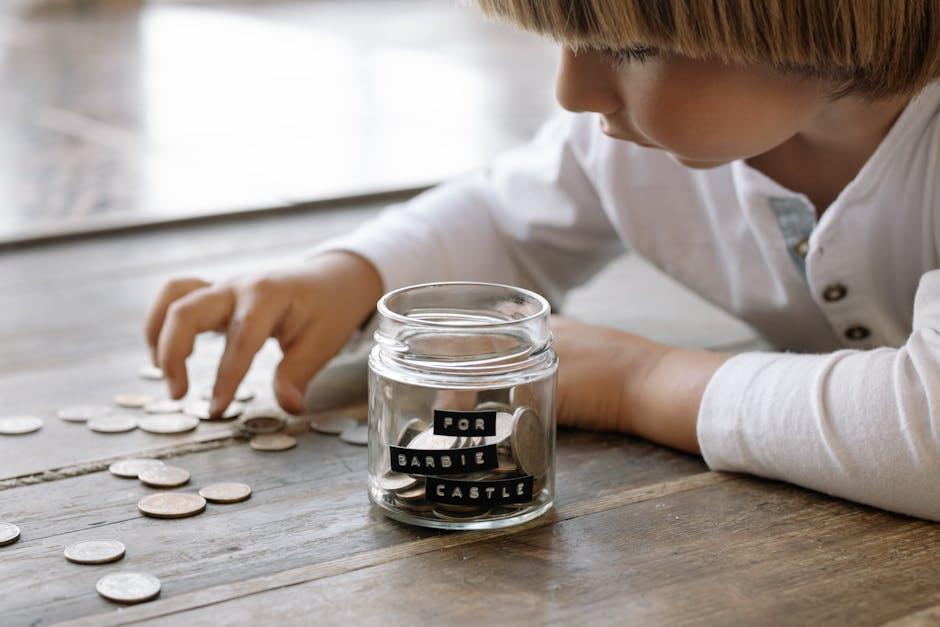
Embarking on a journey to bolster your family’s financial future requires a well-crafted savings plan. Begin by assessing your current financial landscape, setting clear and achievable goals. Analyze your income, expenditures, and existing savings, ensuring a comprehensive understanding of your financial situation. From here, create a budget that prioritizes savings while accommodating necessary expenses. Remember, the key to a successful savings plan is consistency and adaptability.
Consider the following smart choices to enhance your savings strategy:
- Automate your savings: Set up automatic transfers from your checking account to your savings account to ensure regular contributions without the temptation to spend.
- Explore diverse investment options: Look into low-risk investment opportunities such as index funds or government bonds to steadily grow your savings over time.
- Cut unnecessary expenses: Regularly review your spending habits and identify areas where you can cut back, redirecting those funds to your savings.
- Build an emergency fund: Protect your family from unforeseen financial challenges by maintaining a reserve that covers at least three to six months of living expenses.
By incorporating these strategies, you’ll be well on your way to cultivating a robust family savings plan that not only grows over time but also provides financial security and peace of mind.
Monitoring and Adjusting Your Savings Plan for Long-Term Success
To ensure your family savings plan not only survives but thrives over time, it’s crucial to keep a watchful eye and be ready to make necessary adjustments. Regularly reviewing your plan can help identify areas where you might be overspending or under-saving. Consider the following strategies to keep your savings plan aligned with your long-term goals:
- Set Regular Checkpoints: Schedule quarterly or bi-annual reviews of your savings goals and progress. Use this time to assess if your current strategies are effective or if they need tweaking.
- Adjust for Life Changes: Major life events such as the birth of a child, job changes, or unexpected expenses can significantly impact your savings. Be prepared to adjust your plan to accommodate these changes.
- Track Financial Trends: Stay informed about economic trends that could affect your savings, such as inflation or interest rate changes. Adapting your plan in response to these trends can help protect your family’s financial future.
Flexibility is key. By continually monitoring your progress and being open to adjustments, your family savings plan can grow and evolve, securing your financial well-being for years to come.