
In today’s unpredictable financial landscape, unexpected expenses can strike at any moment, challenging even the most meticulously planned budgets. Whether it’s an unforeseen medical bill, a sudden car repair, or an emergency home fix, these financial surprises can disrupt your peace of mind and strain your resources. However, with the right strategies and foresight, you can effectively prepare for these unexpected costs without derailing your financial stability. This guide provides authoritative insights and practical steps to help you build a resilient financial buffer, ensuring that when the unexpected occurs, you’re equipped to handle it confidently and without compromising your financial goals. Emergency Fund for Financial Security”>
Building a Robust Emergency Fund for Financial Security
Establishing a safety net to cover unforeseen expenses is a crucial step towards achieving financial stability. The key is to systematically build your emergency fund without feeling overwhelmed. Start by setting a realistic savings goal. Ideally, aim to save three to six months’ worth of living expenses. Break this goal into manageable monthly targets, ensuring that your savings plan aligns with your current financial situation.
- Automate your savings: Set up automatic transfers from your checking account to a dedicated savings account. This removes the temptation to spend and ensures consistent growth of your fund.
- Cut unnecessary expenses: Analyze your spending habits and identify areas where you can cut back. Redirect these savings towards your emergency fund.
- Utilize windfalls wisely: Whenever you receive unexpected income such as bonuses, tax refunds, or gifts, allocate a portion to your fund.
- Regularly reassess your needs: As your financial situation changes, adjust your savings goal to reflect new expenses or financial obligations.
By adhering to these strategies, you can gradually build a robust emergency fund, offering peace of mind and financial security when life throws you a curveball.
 Budgeting Techniques to Anticipate Surprise Costs”>
Mastering Budgeting Techniques to Anticipate Surprise Costs
In the journey to financial stability, anticipating surprise costs is a skill that separates successful budgeters from the rest. While we can’t predict every unexpected expense, adopting strategic budgeting techniques can safeguard your finances. Start by establishing a contingency fund, a crucial financial buffer that ensures you’re prepared for any unforeseen expenditure. Aim to allocate a portion of your income to this fund consistently. This proactive measure not only helps cover surprise costs but also prevents disruption to your primary budget.
To effectively manage these unforeseen expenses, consider integrating the following tactics into your budgeting strategy:
- Zero-Based Budgeting: Allocate every dollar of your income to specific categories, including savings for unexpected costs, ensuring that no money is unaccounted for.
- Regular Financial Reviews: Conduct monthly reviews of your expenses to identify patterns and adjust your budget accordingly. This will help you anticipate potential areas of overspending.
- Automated Savings: Set up automatic transfers to your contingency fund. This ensures consistent growth of your savings without relying on manual transfers.
By implementing these techniques, you can create a robust financial plan that accommodates surprises without derailing your financial goals. Remember, the key is consistency and adaptability in your budgeting approach.
Strategic Use of Insurance and Credit Options for Unplanned Expenses
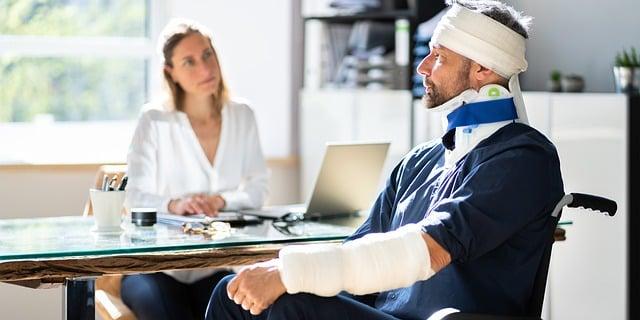
When it comes to managing unforeseen financial demands, leveraging insurance and credit options can serve as a powerful strategy to cushion the blow. Insurance policies such as health, home, or auto coverage can be your first line of defense. Ensure your policies are up-to-date and review them regularly to confirm they meet your current needs. It’s not just about having coverage; it’s about having the right coverage that aligns with potential risks. If you haven’t already, consider adding a rider for specific scenarios like natural disasters or accidents that are more likely to occur in your area.
On the credit front, maintaining a good credit score is essential, as it opens doors to more favorable borrowing terms. Consider having a low-interest credit card or a line of credit as part of your financial toolkit. These can provide immediate access to funds without the high costs associated with payday loans or cash advances. However, use these options judiciously to avoid falling into a debt spiral. Here are some tips for managing credit effectively:
- Pay off balances in full each month to avoid interest charges.
- Keep your credit utilization ratio below 30%.
- Regularly check your credit report for errors and discrepancies.
Leveraging Side Hustles and Investments to Cushion Financial Shocks
In today’s unpredictable economic climate, diversifying your income streams is a savvy strategy to fortify your financial resilience. Side hustles offer a flexible and often lucrative way to supplement your primary income. Whether it’s freelance writing, graphic design, or selling handmade crafts online, the key is to choose something that aligns with your skills and passions. This not only makes the endeavor enjoyable but also sustainable in the long run.
Simultaneously, consider channeling a portion of your earnings into investments that can grow over time. Stocks, bonds, and real estate can serve as robust financial buffers. Here’s how to effectively leverage these tools:
- Start small: Begin with micro-investments if you’re new to the game. Apps and platforms make it easy to invest small amounts.
- Diversify your portfolio: Spread your investments across different asset classes to minimize risk.
- Stay informed: Keep abreast of market trends and adjust your strategy accordingly.
By thoughtfully combining side hustles and strategic investments, you can create a safety net that cushions the blow of unexpected expenses, without straining your existing budget.