
Navigating the college application process can be both exhilarating and overwhelming, with numerous details to consider and decisions to make. One crucial aspect that often goes overlooked is the financial commitment required for application fees. These fees can quickly add up, especially if you’re applying to multiple institutions. However, with strategic planning and informed decision-making, you can effectively estimate and manage these costs without derailing your budget. In this article, we’ll guide you through the steps to accurately estimate college application fees and offer practical tips on how to save money during this pivotal stage of your academic journey. Whether you’re a student or a parent, this comprehensive guide will empower you to approach college applications with confidence and financial savvy.
Understanding the True Cost of College Applications
When planning for college, understanding the multifaceted expenses of the application process is crucial. Application fees can vary significantly between institutions, often ranging from $50 to $100 per application. But these fees are just the tip of the iceberg. Applicants should also consider additional costs such as standardized test fees, transcript fees, and travel expenses for campus visits. Moreover, many students overlook the cost of sending standardized test scores to multiple schools, which can add up quickly.
To effectively manage these expenses, start by creating a detailed budget. Consider these key areas:
- Application Fees: Multiply the number of schools you’re applying to by the average application fee.
- Testing Costs: Include fees for the SAT, ACT, or any required subject tests, plus potential retakes.
- Transcript and Document Fees: Check with your high school for any charges related to sending official documents.
- Campus Visits: Estimate travel, lodging, and meal costs if you plan to visit schools in person.
- Score Sending Fees: Remember to include the cost of sending your test scores to each college.
By proactively accounting for these expenses, you can create a financial plan that ensures you’re prepared for every step of the college application journey.
Strategically Budgeting for Application Fees
Planning ahead for the costs associated with college applications is crucial to avoid any financial surprises. Begin by researching the application fees for each college on your list, as they can vary widely. It’s a good idea to create a spreadsheet or document to track these expenses. This document should include the name of each college, the application fee, and any additional costs such as standardized test score submissions or portfolio reviews. Staying organized will help you see the big picture and adjust your application strategy if needed.
Consider the following tips to effectively manage these expenses:
- Prioritize your applications: Focus on a mix of reach, match, and safety schools, and consider applying to schools that offer fee waivers.
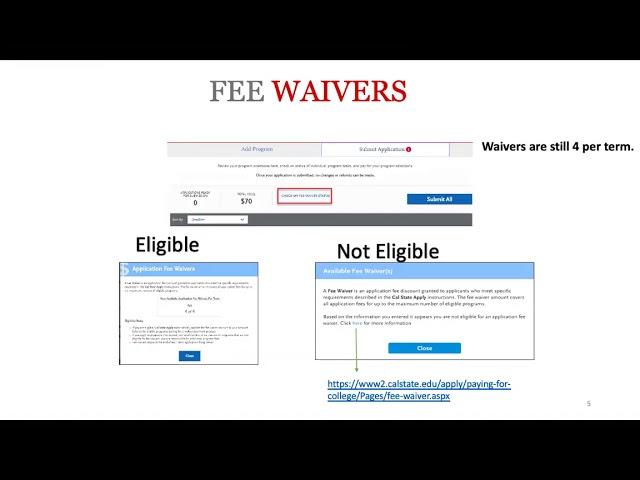
- Leverage fee waivers: Many colleges provide waivers based on financial need or if you attend certain college fairs or campus tours. Check the eligibility criteria early.
- Set aside a monthly budget: Allocate a portion of your savings specifically for application fees. This proactive approach prevents last-minute scrambles.
By being strategic and disciplined, you can manage application fees without stress, ensuring that financial constraints do not limit your educational opportunities.
Effective Ways to Reduce College Application Expenses
Applying to college can be a financially demanding process, but there are several strategies to help manage these costs effectively. Start by narrowing down your list of potential colleges to a realistic number. Consider factors such as location, programs offered, and financial aid opportunities to create a focused list of schools that align with your goals. This targeted approach reduces the number of application fees you need to pay and increases the quality of each application.
Another cost-saving strategy is to take advantage of application fee waivers. Many colleges offer waivers for students who demonstrate financial need. Additionally, participating in programs like the College Board’s SAT Fee Waiver program or the Common Application can provide access to fee waivers. Reach out to your high school counselor for guidance on how to apply for these waivers. Furthermore, keep an eye on early application deadlines, as some colleges offer discounts or waive fees for early submissions. Lastly, explore the option of community college applications, which often have lower fees and provide a cost-effective pathway to a four-year degree.
Maximizing Your Savings with Smart Application Strategies
Applying to college can be a costly endeavor, but with a strategic approach, you can keep your expenses in check. Begin by researching application fees for each college on your list, as these can vary significantly. Some institutions may offer fee waivers based on financial need or for students who apply early, so it’s crucial to explore these options. Additionally, consider applying to a mix of public and private schools, as public universities often have lower fees.
- Create a detailed spreadsheet listing each college’s application fee.
- Investigate fee waiver eligibility for each school.
- Prioritize applications to schools offering waivers or lower fees.
- Set a savings goal based on your estimated total fees.
To further stretch your savings, limit your applications to schools that truly fit your academic and personal goals. This not only helps reduce costs but also increases your chances of acceptance to a school where you’ll thrive. Remember, a focused and informed approach can make the college application process more affordable and less stressful.