
As you approach the pinnacle of your career, securing a financially stable and comfortable retirement becomes a crucial priority. For high-income earners, the strategies for safeguarding your future extend beyond conventional savings plans. With greater financial resources at your disposal, the opportunity to craft a retirement strategy that not only preserves your wealth but also enhances your lifestyle is within reach. This guide will walk you through the most effective retirement strategies tailored specifically for high-income earners, empowering you to make informed decisions with confidence. From maximizing tax-advantaged accounts to diversifying investment portfolios, discover how to leverage your earnings to build a robust and resilient retirement plan that aligns with your goals and aspirations.
Maximizing Tax-Advantaged Accounts for High Earners
High-income earners have a unique opportunity to leverage tax-advantaged accounts to bolster their retirement savings. The first step is to maximize contributions to 401(k) plans. This not only reduces taxable income but also allows for substantial growth over time. Additionally, consider utilizing backdoor Roth IRAs, a strategy that involves converting a traditional IRA to a Roth IRA, enabling tax-free growth and withdrawals. This can be especially beneficial for those who exceed the income limits for direct Roth IRA contributions.
Moreover, Health Savings Accounts (HSAs) offer another avenue for tax-advantaged savings. Contributions are tax-deductible, and withdrawals for qualified medical expenses are tax-free. For high earners, using an HSA as a retirement account can be a smart move, as funds can be invested and grow tax-free. When strategizing, it’s crucial to take advantage of these accounts to optimize both tax savings and retirement security.
- Maximize 401(k) contributions
- Utilize backdoor Roth IRAs
- Consider Health Savings Accounts (HSAs)
Diversifying Investments to Protect Wealth
For high-income earners, the key to safeguarding wealth lies in the strategic diversification of investments. By spreading assets across a variety of investment vehicles, you can reduce risk and enhance potential returns. Here are some ways to diversify effectively:
- Stocks and Bonds: A balanced portfolio of stocks and bonds is essential. While stocks offer growth potential, bonds provide stability, especially during market downturns.
- Real Estate: Investing in real estate, whether through direct property ownership or Real Estate Investment Trusts (REITs), can provide a steady income stream and hedge against inflation.
- Alternative Investments: Consider diversifying with alternative assets like commodities, private equity, or hedge funds. These can offer unique opportunities and reduce correlation with traditional markets.
- International Markets: Don’t overlook opportunities in international markets. Global diversification can help mitigate country-specific risks and tap into emerging market growth.
By carefully selecting a mix of these assets, high-income earners can create a robust investment strategy that not only protects their wealth but also positions them for future financial success. Remember, the ultimate goal is to build a portfolio that aligns with your risk tolerance, financial goals, and retirement timeline.
Strategic Real Estate Investments for Long-Term Growth
Investing in real estate can be a powerful strategy for high-income earners aiming for long-term financial security and growth. By carefully selecting properties, you can not only generate steady passive income but also benefit from potential appreciation in value. Diversification is key; consider a mix of residential, commercial, and even industrial properties to spread risk and capture different market opportunities. High-income earners should leverage their financial strength to invest in prime locations where property values are more likely to appreciate.
Here are some strategic approaches to consider:
- Buy and Hold: Acquire properties in high-demand areas and hold onto them to benefit from long-term appreciation.
- Rental Properties: Invest in rental units to create a consistent income stream, taking advantage of tax benefits and potential appreciation.
- REITs (Real Estate Investment Trusts): For those looking to avoid the hassles of property management, REITs offer a way to invest in real estate without direct ownership.
- Fix and Flip: Purchase undervalued properties, renovate them, and sell for a profit. This requires a keen eye for value and potential.
By implementing these strategies, high-income earners can craft a real estate portfolio that not only safeguards their wealth but also enhances it over time, making it a cornerstone of a robust retirement plan.
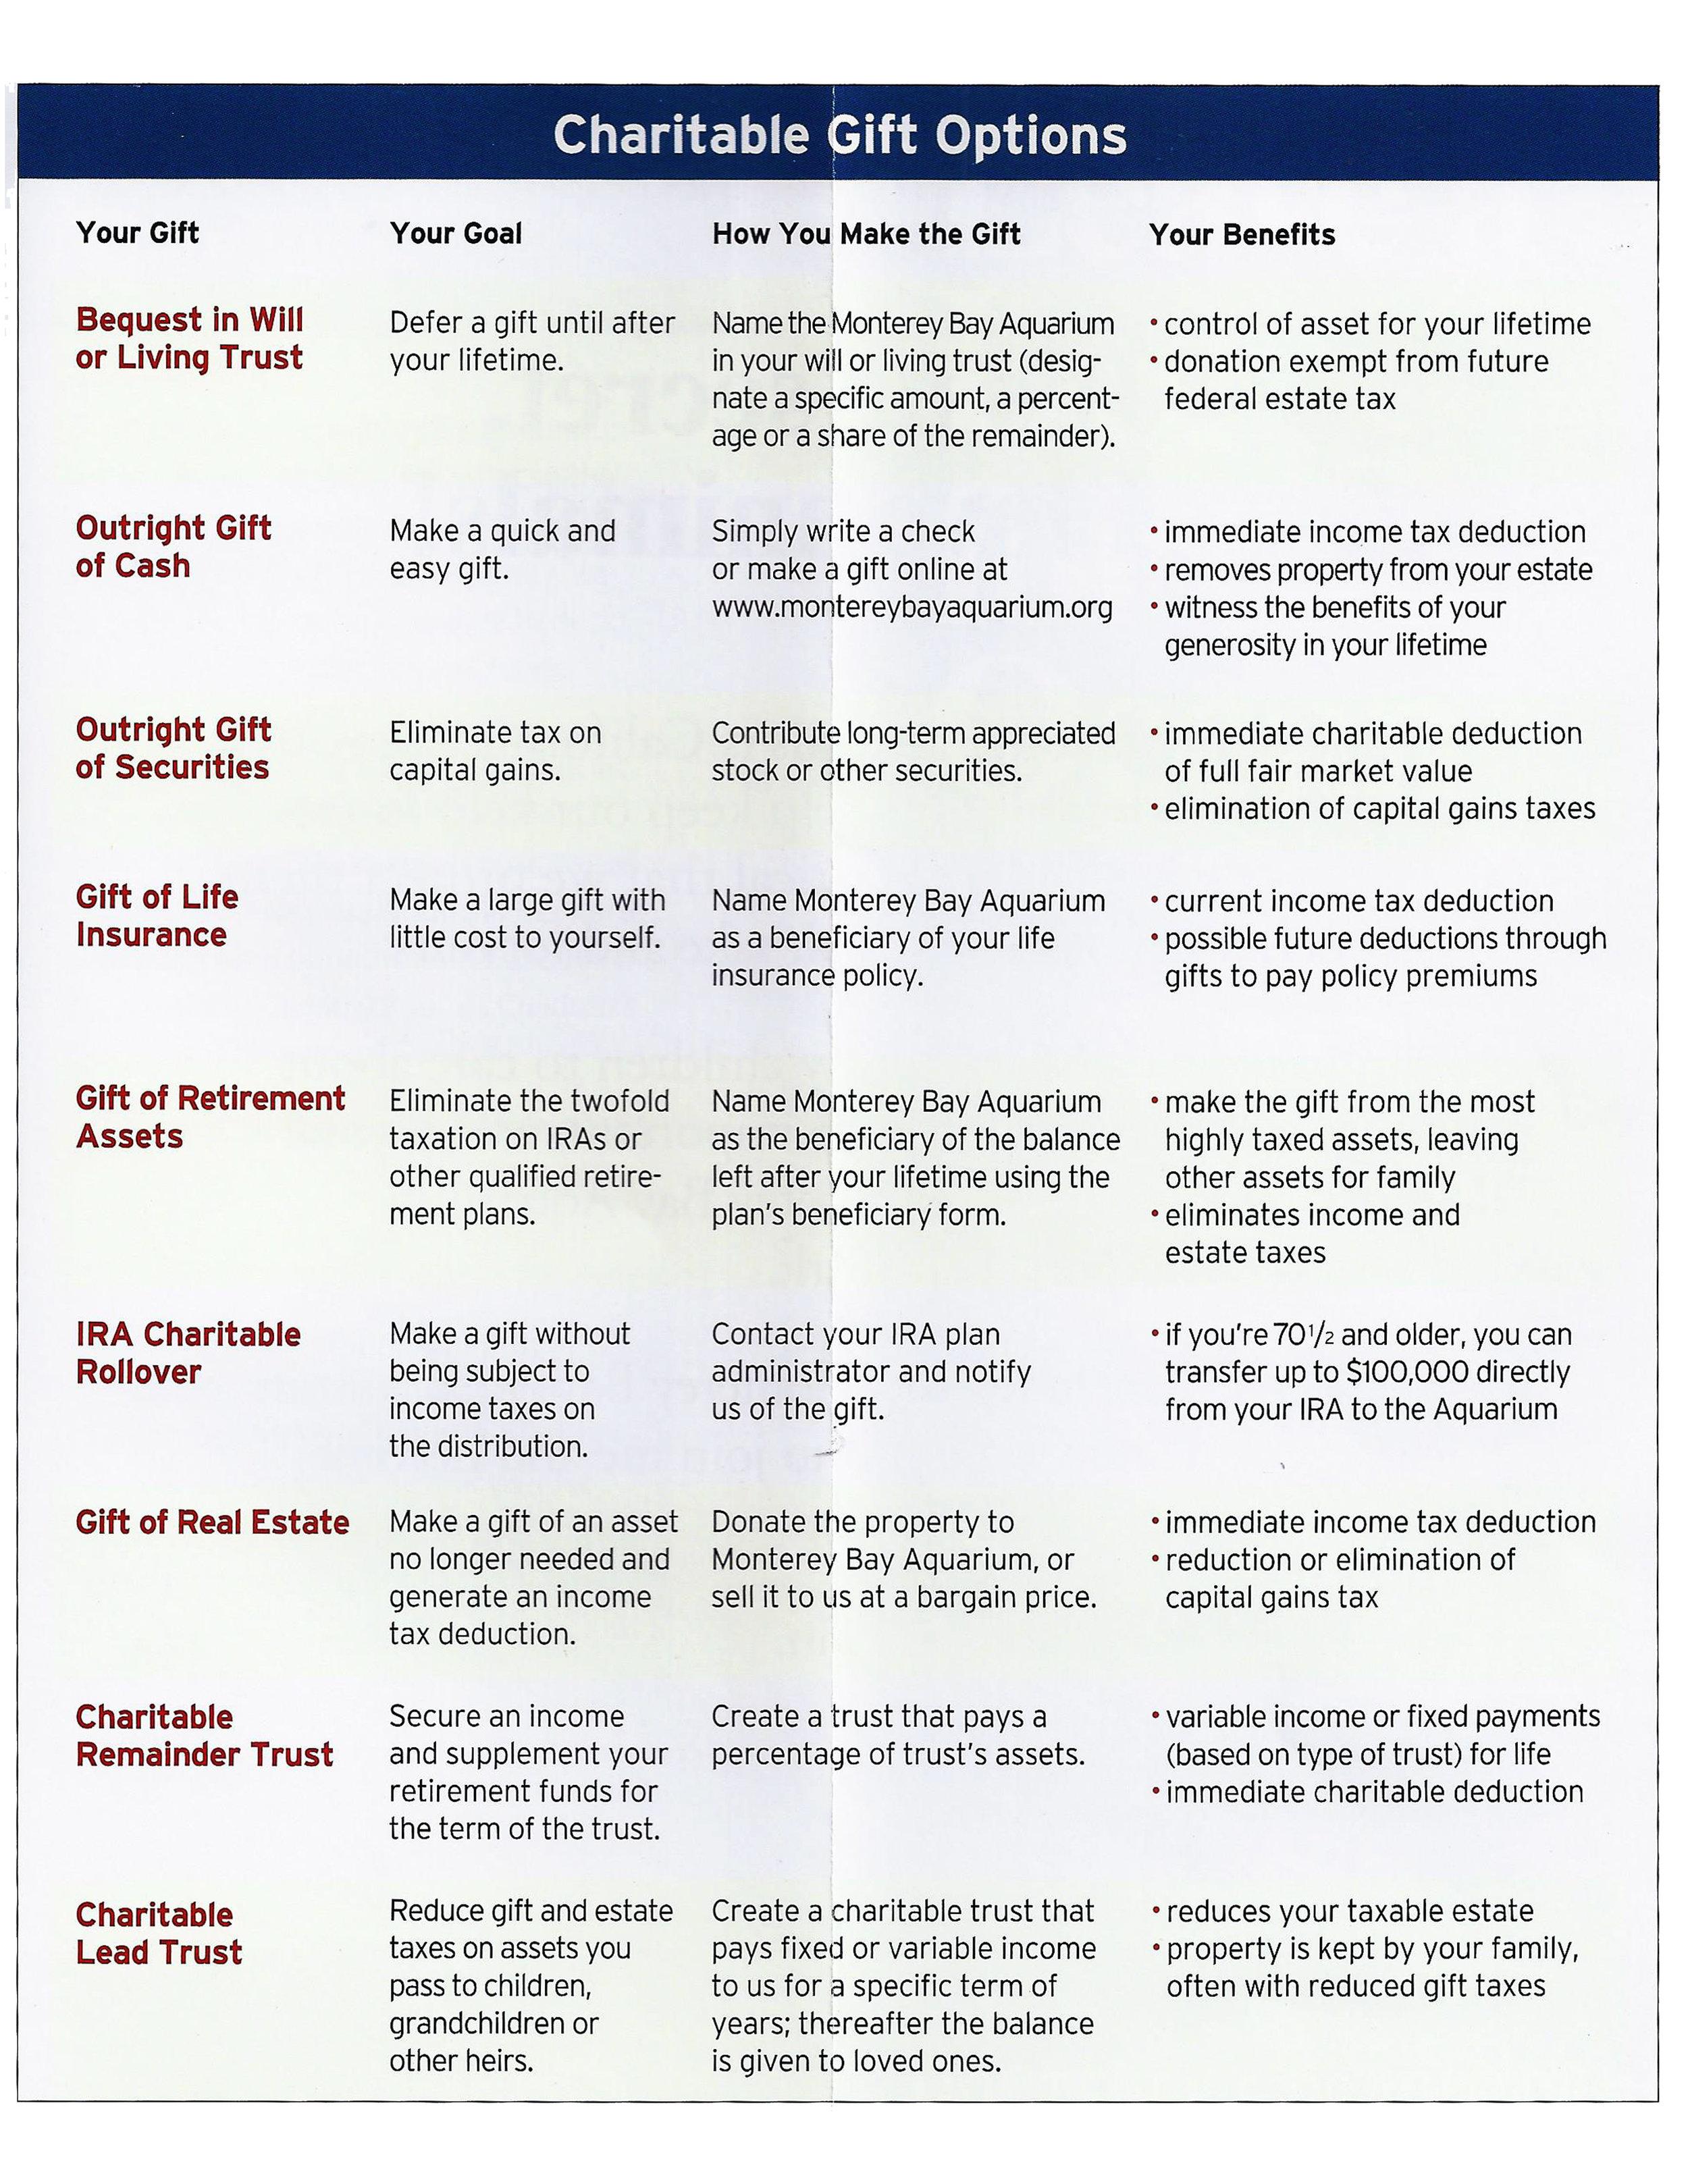
Crafting a Charitable Giving Plan to Reduce Tax Liabilities
High-income earners looking to minimize tax liabilities while making a positive impact should consider integrating philanthropy into their financial strategy. Charitable giving can be a powerful tool to not only support causes you care about but also to optimize your tax situation. Here are some key steps to effectively craft a charitable giving plan:
- Identify Your Causes: Determine which charities align with your personal values and interests. Focusing on a few key organizations can make your contributions more impactful.
- Choose the Right Donation Method: Consider donating appreciated assets like stocks, which can help avoid capital gains taxes while still providing a full-value deduction.
- Establish a Donor-Advised Fund (DAF): A DAF allows you to make a charitable contribution, receive an immediate tax deduction, and then recommend grants from the fund over time.
- Utilize Qualified Charitable Distributions (QCDs): If you’re 70½ or older, you can transfer up to $100,000 annually from your IRA directly to charity, which can satisfy your required minimum distributions without increasing your taxable income.
By strategically planning your charitable contributions, you can support your favorite causes while effectively reducing your taxable income, making it a win-win for both you and the community.